


01. Edit your 2013 form 709 instructions online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send 2013 form 706 via email, link, or fax. You can also download it, export it or print it out.
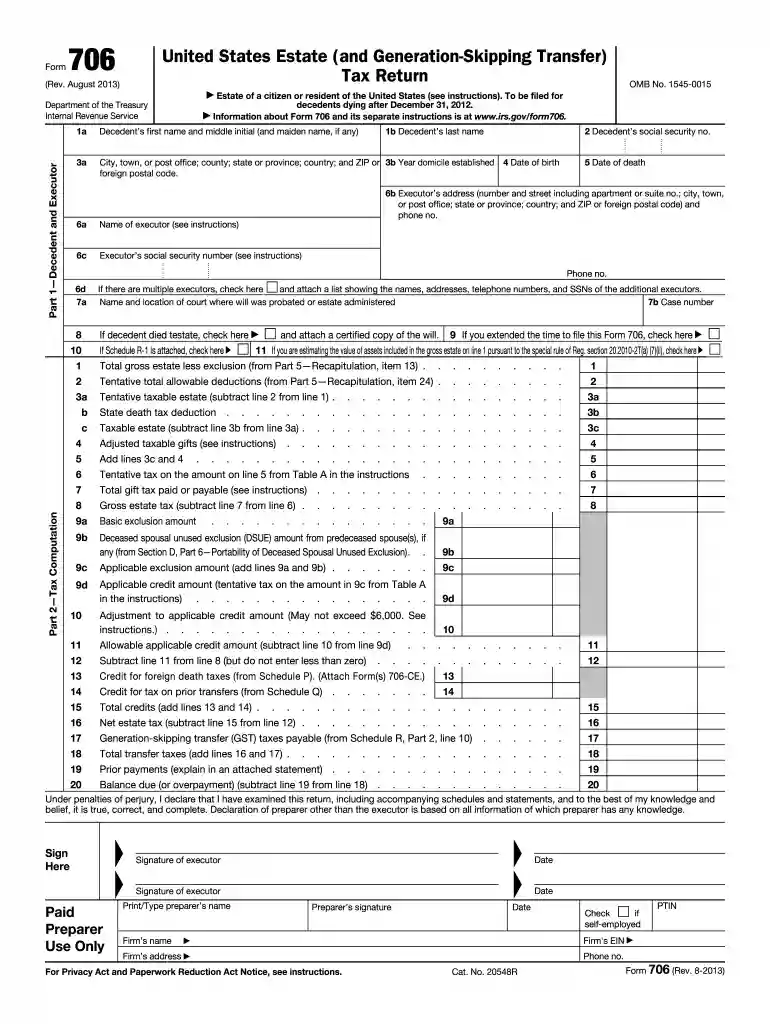
Form 706, officially known as the United States Estate (and Generation-Skipping Transfer) Tax Return, is used to determine the estate tax liability of deceased individuals with estates surpassing the federal estate tax exemption threshold. Relevant for estates of individuals who passed away after December 31, 2012, it serves a critical role in reporting the fair market value of the decedent's assets. It includes a comprehensive evaluation of various components, such as bank accounts, real estate, and closely held businesses, to determine the correct tax liability. The form also facilitates the portability election, allowing a surviving spouse to apply the deceased spousal unused exclusion (DSUE) amount to their future estate and gift tax returns.
Completing Form 706 involves several important sections that require detailed information:
Completing Form 706 requires careful attention to detail. Follow these steps to ensure accuracy:
Form 706 is primarily used by the executors of estates of deceased individuals in instances where the estate's value exceeds the federal exemption threshold. Executors, often family members or estate attorneys, complete the form not only to comply with federal tax regulations but also to efficiently manage the deceased’s financial legacy. It is especially relevant when involving more complex estates with multiple asset types or significant liabilities, ensuring all components are considered in the estate valuation process.
The IRS mandates that Form 706 be filed nine months after the decedent's death. An extension of six months can be requested by submitting Form 4768. It is imperative to adhere to these deadlines to avoid penalties and interest on underpaid taxes. The IRS provides a comprehensive set of instructions for completing Form 706, which outlines specific rules for asset valuation, filing procedures, and what documentation is required.
When submitting Form 706, executors need to include several essential documents:
While Form 706 is standardized at the federal level, certain states have additional estate or inheritance tax return forms. Executors should verify state-specific requirements, as states like New York and New Jersey have unique forms for state-level estate tax reporting. These forms often mirror the federal process but contain state-specific thresholds, rates, and deductions that can affect the overall tax strategy.
Failure to file Form 706 on time or incorrect filing can lead to significant penalties. The IRS may impose late filing penalties, which could amount to 5% of the tax due per month, up to 25%. There are also potential accuracy-related penalties if there is a substantial understatement of estate tax due to negligence or ignorance of tax laws. Therefore, accuracy and punctuality are critical in estate tax administration to minimize financial risks and ensure compliance with regulations.
We've got more versions of the 2013 form 709 instructions form. Select the right 2013 form 709 instructions version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Form 706 (Rev 8-2013). BAA For Privacy Act and Paperwork Reduction Act Notice, see instructions. Page 2. Form 706 (Rev 8-2013) Form 706 (Rev 8-2013).Read more
Form 706 (Rev. 8-2013). 4. Personal property used in a qualified use and passing to qualified heirs. A. Schedule and item number from Form 706. B. AdjustedRead more


