




01. Edit your caution up full form online
Type text, add images, blackout confidential details, add comments, highlights and more.

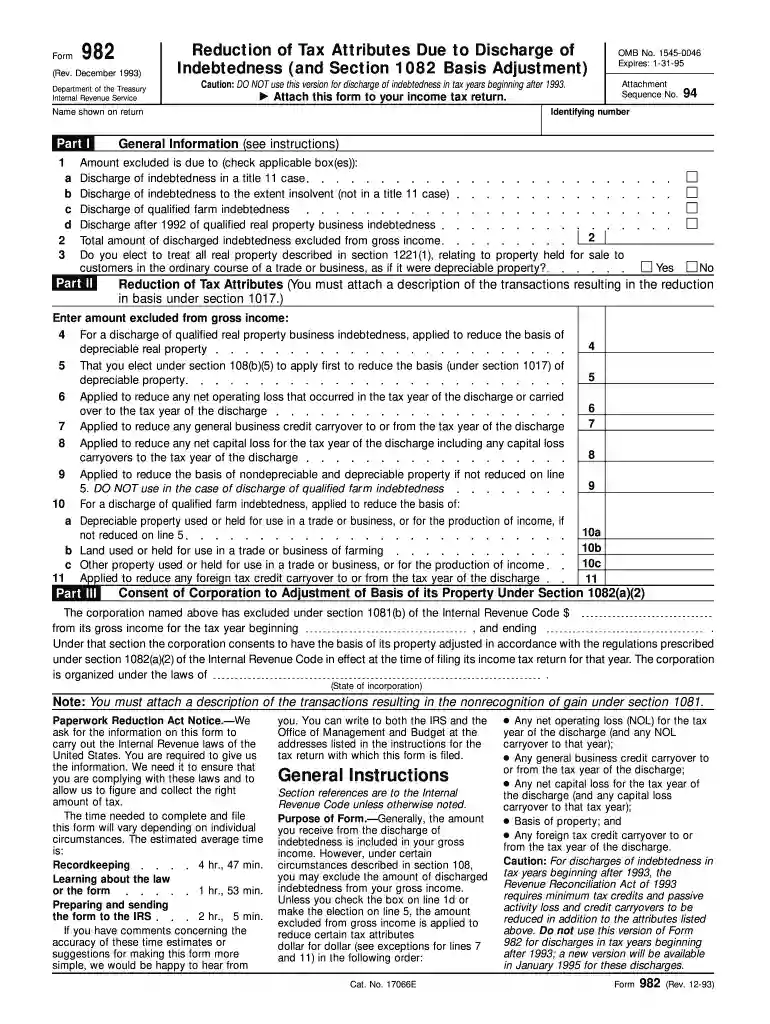
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
The form "Caution: DO NOT use this version for discharge of indebtedness in tax years beginning after 1993" refers to a document that was once utilized by taxpayers to report the reduction of tax attributes related to indebtedness discharge. This form plays a role in the adjustment of tax obligations under specific conditions outlined in the Internal Revenue Code. The essential detail of this form is the warning against its use for tax years starting after 1993, indicating that changes in tax laws or regulations have rendered it obsolete for those years.
Although the form should not be used for tax years beginning after 1993, understanding its previous uses can offer insights into discharge of indebtedness processes.
The Internal Revenue Service (IRS) provides specific guidelines for handling indebtedness discharge, primarily via other forms and procedures for post-1993 tax years.
Debt Details: Information about the discharged debt that is to be excluded from income.
Tax Attribute Reductions: Sections to report reductions such as basis in property or net operating losses.
Legal Compliance: Elements to ensure the taxpayer was adhering to the tax laws relevant before 1994.
For forms related to discharge of indebtedness, including Form 982 which replaced the obsolete version, it is critical to adhere to IRS filing deadlines.
When dealing with discharge of indebtedness, specific documentation supports claims of income exclusion and attribute reduction.
Failure to adhere to the IRS guidelines for forms related to debt discharge can result in significant penalties.
Monetary Fines: IRS may impose fines for failing to report or incorrectly applying attribute reductions.
Legal Consequences: Incorrect filing or reliance on outdated forms may lead to audits or legal action.
Accuracy-related Penalty: Taxpayers providing incorrect information on modern forms parallel to the obsolete versions face penalties for inaccuracies.
Before its obsolescence, specific categories of taxpayers frequently utilized the form for debt-related tax adjustments.
Historically, utilizing the form required strict adherence to legal guidelines to ensure the justified discharge of indebtedness and corresponding tax adjustments.
Taxpayers now use different documentation to report discharge of indebtedness, in alignment with changes in tax law.
With technological progress, filing processes for related forms have shifted predominantly towards digital platforms, supported by IRS and tax preparation software.
Efficiency: Easier document management and submission.
Accuracy: Software reduces errors and ensures compliance with latest IRS guidelines.
Accessibility: Allows taxpayers across the United States to file from any location with internet access.
Certain businesses are more likely to encounter scenarios necessitating report of indebtedness discharge.
These evolutionary changes in filing practices highlight the importance of staying informed about tax regulatory updates and adhering to the most current procedures and documentation such as Form 982 in lieu of the obsolete form discussed.
We've got more versions of the caution up full form form. Select the right caution up full form version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
by RG Saharovich 2016 Cited by 5 ABSTRACT. Prior to Congress passing BAPCPA in 2005, an individual was able to discharge debt related to a tax return filed after April 15thRead more
Oct 5, 2018 SHORT TITLE; TABLE OF CONTENTS. (a) SHORT TITLE.This Act may be cited as the FAA Reauthor- ization Act of 2018Read more
Do not use this version of Form. 982 for discharges in tax years beginning after 1993; a new version will be available in January 1995 for these discharges. youRead more


