



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

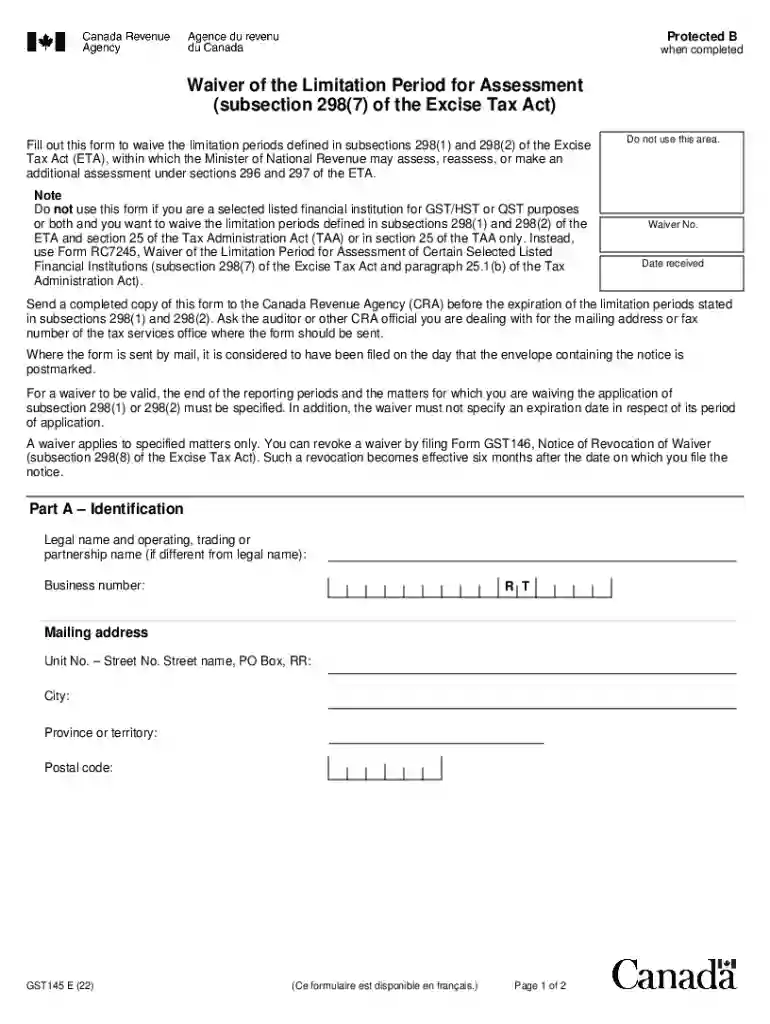
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
The "Waiver of the Limitation Period for Assessment" refers to a legal instrument used within the United States taxation system. This waiver allows taxpayers to voluntarily relinquish their right to a limitation period for tax assessments. Under certain sections of the Excise Tax Act, it provides the Internal Revenue Service (IRS) with an extended period beyond the standard statutes to assess or reassess a taxpayer's returns. This is particularly relevant when discrepancies or audits are anticipated, or where additional time is beneficial for both the taxpayer and the IRS to review and finalize any tax obligations or errors.
Utilizing the waiver involves a few critical steps to ensure compliance with legal requirements:
Completing the waiver form involves several detailed steps:
Prepare Necessary Information
Gather all relevant tax documents and personal information before beginning the form.
Complete Identifying Information
Enter taxpayer information, including name, Social Security Number, or business identification number.
Detail Tax Periods
Clearly specify the tax period(s) for which the limitation waiver applies.
Sign the Waiver
Both the taxpayer and the IRS representative must sign the form to validate the waiver.
Retain Copies
Keep copies of the signed waiver for both personal records and audit trails.
The waiver plays a crucial role in legal and administrative procedures:
IRS Authority: Grants legal authority to IRS to extend the assessment period.
Protection from Legal Disputes: Helpful in case of legal disputes related to tax assessments.
Support for Audit Processes: Facilitates a smoother audit process by integrating necessary time extensions.
Case Study: Often used in corporate tax filings where financial complexities may take longer to resolve.
Several entities and individuals may find this waiver beneficial for extending their assessment periods:
Corporations and LLCs: Large businesses that often face detailed IRS audits.
Self-employed Individuals: Those with complicated tax structures who might require additional time for accurate documentation.
Financially Complex Filers: Individuals or entities with multiple income streams.
Example: A multinational corporation engaged in international trade may use the waiver to manage intricate tax obligations.

Understanding the core components helps in navigating and implementing the waiver effectively:
Identifying Information: Critical for aligning with IRS records.
Scope of Waiver: Details exactly what periods and what items are being waived.
Duration: Specifies the time period for which the waiver is applicable.
Practical Consideration: Specific elements need accurate detailing to avoid any future legal challenges.
Key terminology involved in the waiver process includes:
Assessment Period: The time during which the IRS is allowed to assess or collect taxes.
Excise Tax Act: The legislative framework governing tax assessment procedures.
Retroactive Adjustments: Changes that apply backward to a specified tax period.
Example Application: Retrospective adjustments as ruled under certain IRS provisions.
Understanding software that can aid in processing and managing the waiver document:
TurboTax & QuickBooks: These popular tax preparation software offer features to assist in generating, completing, and managing the waiver form.
Integration and Ease: Ensure accurate transfer of needed financial data.
Alerts: Many software provide built-in notifications for review and submission timelines.
User Tip: Utilize compatible software for seamless compliance and record-keeping.
By providing a thorough guide on using and understanding the Waiver of the Limitation Period for Assessment, taxpayers can navigate the complexities with confidence and clarity.
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Jun 5, 1997 The policies and procedures set forth here are intended as guidance to Agency and other government employees.Read more
If the IRS proposes a waiver to extend the ASED, you can negotiate the proposed time limitation to assess, or refuse to sign the waiver. If you omitted moreRead more
The taxpayer may claim a refund during the period of the waiver. (4) Amended returns filed within 60 days of the expiration of the statute of limitations forRead more


