


01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
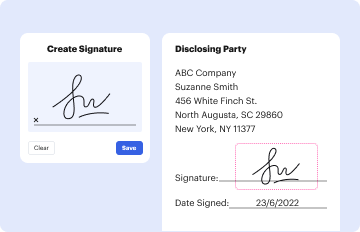
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
The Business & Occupation (B&O) Activities Return is a tax form used in the State of Washington to report and remit business taxes. This form requires businesses to itemize their revenue from different activities performed within the state, identify any possible deductions, and calculate the total tax due. This document serves as a vital tool for businesses to comply with Washington State’s taxation policies, ensuring accurate reporting and payment of taxes based on their operations.
Completing the B&O Activities Return involves several detailed steps to ensure accurate reporting:
Several documents are essential for accurately completing the B&O Activities Return:
Staying informed about filing deadlines is crucial for compliance:
Non-compliance with B&O tax filing can result in significant penalties:
Washington State allows multiple submission avenues for the Business & Occupation Activities Return:
The Washington State Department of Revenue (DOR) is responsible for issuing and managing the B&O Activities Return.
The B&O Activities Return is primarily used by:
With a detailed understanding of each of these sections and their implications, businesses can streamline their tax filing process and minimize risks associated with non-compliance.
We've got more versions of the Business Occupation Activities Return - Washington State - dor wa form. Select the right Business Occupation Activities Return - Washington State - dor wa version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
This rule explains the business and occupation (BO) tax credit for small businesses provided by RCW 82.04.4451.
Washingtons BO tax is calculated on the gross income from activities. This means there are no deductions from the BO tax for labor, materials, taxes, or
Jan 30, 2018 If you choose to report, rather than exclude, your taxable gain, you can undo that choice by filing an amended return within 3 years of the due


