

Here's how it works
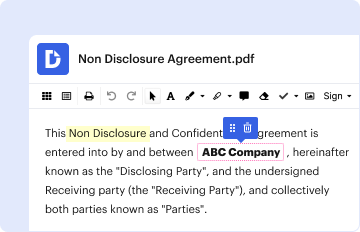
01. Edit your irs publication 584 b online
Type text, add images, blackout confidential details, add comments, highlights and more.
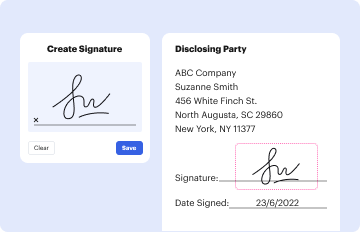
02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
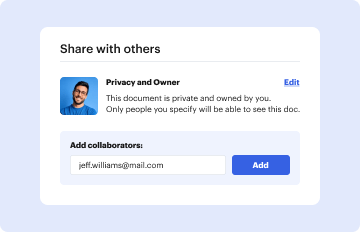
03. Share your form with others
Send irs casualty loss worksheet via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out publication 584 with our platform
- Click ‘Get Form’ to open publication 584 in the editor.
- Begin by reading the introduction section to understand the purpose of the workbook, which is to help you calculate losses on personal-use property due to disasters, casualties, or thefts.
- Familiarize yourself with the definitions of 'cost or other basis' and 'fair market value' as these are crucial for filling out the schedules.
- Fill out Schedules 1 through 20. Each schedule corresponds to different categories of personal property. Enter details such as item description, cost basis, fair market values before and after the incident, and any insurance reimbursements.
- Refer to the instructions for Form 4684 after completing your schedules. This form is necessary for reporting your calculated losses based on the information you've gathered.
- Finally, transfer your entries from Schedules 1 through 20 into Form 4684 as instructed in publication 584.
Start using our platform today for free to streamline your document editing and form completion!
Fill out publication 584 online
It's free
It's free
See more publication 584 versions
We've got more versions of the publication 584 form. Select the right publication 584 version from the list and start editing it straight away!
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
What qualifies as a casualty loss deduction (IRS)?
A casualty loss can result from the damage, destruction, or loss of your property from any sudden, unexpected, or unusual event such as a flood, hurricane, tornado, fire, earthquake, or volcanic eruption. A casualty doesnt include normal wear and tear or progressive deterioration.
What are the two main limitations applied to casualty and theft loss deductions for personal use property?
For taxpayers experiencing loss of personal use property in a federally declared disaster area, two limitations apply to a casualty loss deduction: (1) the loss must exceed $100, and (2) aggregate losses may be deducted only to the extent they exceed 10 percent of adjusted gross income.
How do I deduct casualty loss on rental property?
If your rental property is completely destroyed or stolen, your deduction is calculated as follows: Adjusted basis - Salvage value - Insurance proceeds = Deductible loss.
How do you prove casualty loss?
To prove the amount of your loss, you should have: Purchase receipts for the affected property. Receipts for improvements made to the affected property. Pre- and post-casualty appraisals for the affected property.
What qualifies for casualty loss deduction under IRS code section 165?
165 provides a deduction for casualty losses that are incurred (1) in a trade or business; (2) in a transaction entered into for profit, though not connected with a trade or business; and (3) except as limited, not connected with a trade or business or a transaction entered into for profit, if such loss arises from
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


People also ask
What is the IRS publication home sale exclusion?
That means if you sell your home for a gain of less than $250,000 (or $500,000 if married, filing jointly), you wont be obligated to pay capital gains tax on that amount. However, there are certain criteria you must meet to qualify for the home sale exclusion.
What is the IRS publication for moving expenses?
About Form 3903, Moving Expenses | Internal Revenue Service.