




Here's how it works

01. Edit your fsa 2254 online
Type text, add images, blackout confidential details, add comments, highlights and more.

02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

03. Share your form with others
Send forms sc egov usda via email, link, or fax. You can also download it, export it or print it out.
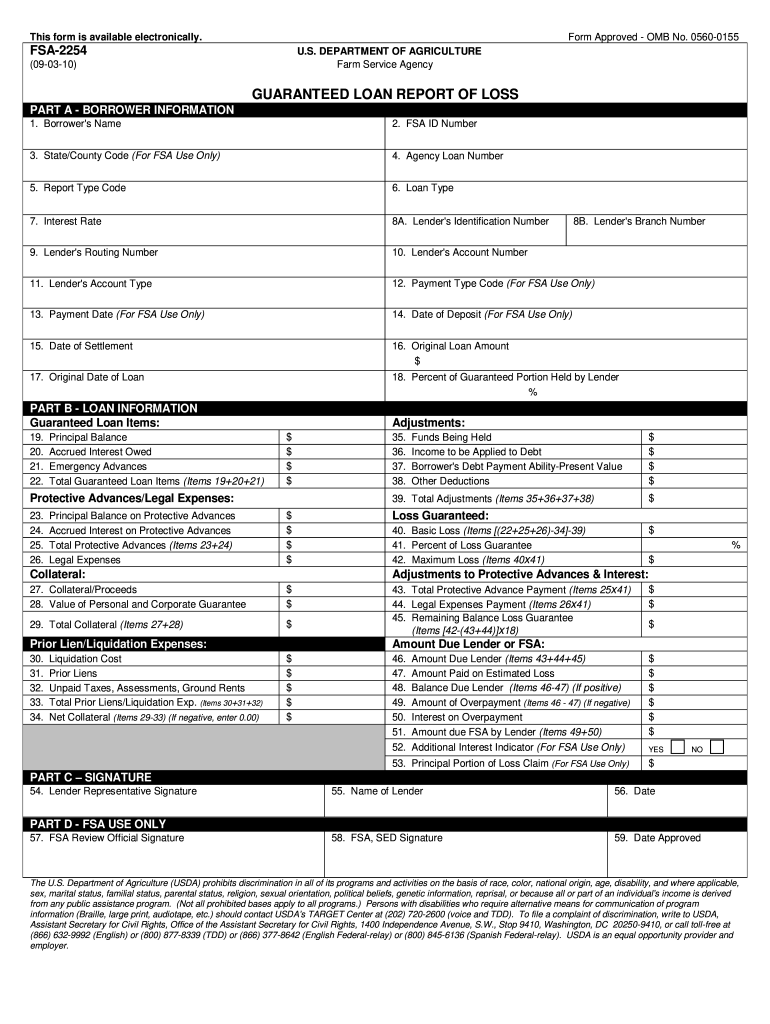
How to use or fill out GUARANTEED LOAN REPORT OF LOSS - forms sc egov usda with our platform

- Click ‘Get Form’ to open it in the editor.
- Begin with Part A, entering the Borrower's Name and FSA ID Number. Ensure accuracy as these are critical for identification.
- Continue filling in the Agency Loan Number and Report Type Code. These fields help categorize your report correctly.
- In Part B, list all Guaranteed Loan Items, including Principal Balance and Accrued Interest Owed. This section is essential for calculating total losses.
- Complete the adjustments section by detailing any Protective Advances or Legal Expenses incurred during the loan process.
- Finally, sign in Part C, ensuring that both the Lender Representative and FSA signatures are included before submission.
Start using our platform today to streamline your form completion process for free!
Fill out GUARANTEED LOAN REPORT OF LOSS - forms sc egov usda online
It's free
It's free
See more GUARANTEED LOAN REPORT OF LOSS - forms sc egov usda versions
We've got more versions of the GUARANTEED LOAN REPORT OF LOSS - forms sc egov usda form. Select the right GUARANTEED LOAN REPORT OF LOSS - forms sc egov usda version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2010 | 4 Satisfied (47 Votes) |
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
What are the different types of USDA loans?
The U.S. Department of Agriculture (USDA) has two home loan programs: the Section 502 Guaranteed Loan and the Section 502 Direct Loan. Both help eligible buyers with low to moderate incomes to purchase homes in rural areas and small towns. With a guaranteed loan, 90% of the loan amount is backed by the USDA.
What is a USDA guarantee loan?
The U.S. Department of Agricultures (USDA) Single Family Housing Guaranteed Loan Program (Guaranteed Loan Program) is designed to serve eli- gible rural residents with incomes below 115 percent of area median income or AMI (see USDA definition in overview) who are unable to obtain adequate hous- ing through
Is it difficult to get an USDA loan?
Approved USDA loan lenders typically require a minimum credit score of at least 620 to get a USDA home loan. However, the USDA doesnt have a minimum credit score, so borrowers with scores below 620 may still be eligible for a USDA-backed mortgage. If your credit score is below 620, theres still hope.
What credit score is needed for a USDA direct loan?
Credit: Applicants must be unable to obtain a loan from other sources on reasonable terms and condi- tions. However, applicants must have reasonable credit histories as determined by USDAs loan officers. Applicants with a reliable credit score of 640 typically qualify for a streamlined credit review.
What is the difference between a direct USDA loan and a guaranteed USDA loan?
The primary difference between USDA direct loans and USDA guaranteed loans is who funds the actual loan. With the USDA direct loan, the USDA acts as the lender. Conversely, with the guaranteed loan program, private lenders fund the loan while the USDA backs each loan against default.
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


People also ask
What is the difference between USDA guaranteed and USDA direct loan?
The main difference is who provides the loan and who qualifies for it. Direct Loans are for very low-income buyers and come straight from the USDA. Guaranteed Loans are for low to moderate-income buyers and come from regular lenders, with the USDA backing them up.