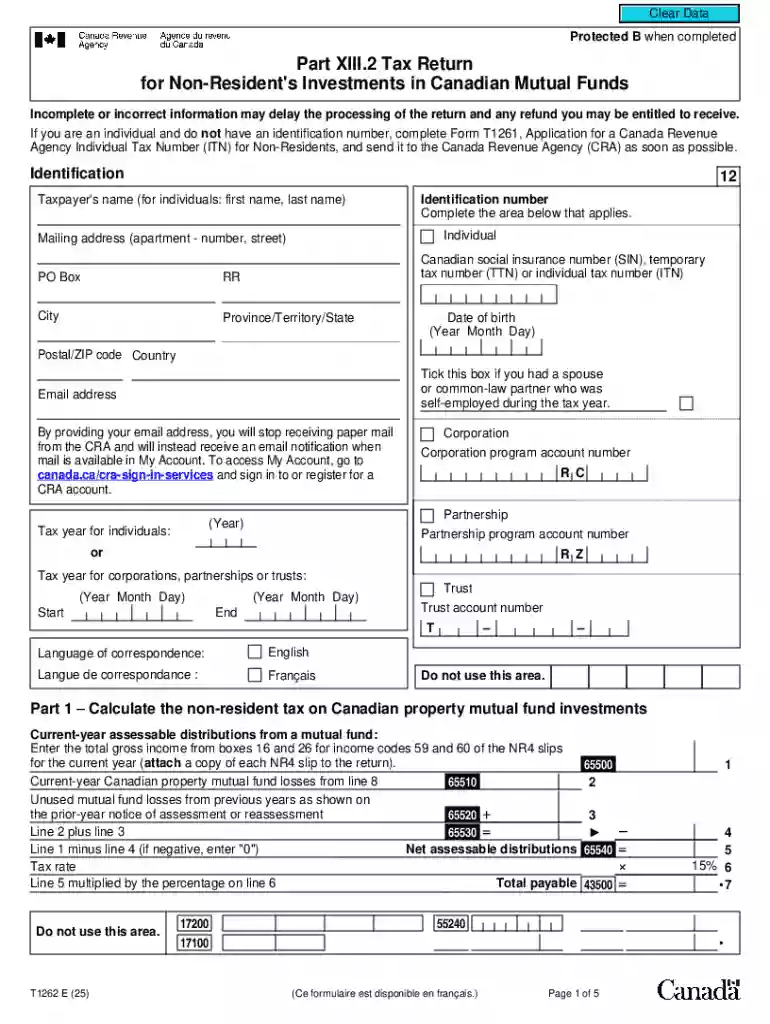
Part XIII 2 Tax Return for Non-Resident's Investments in Canadian Mutual Funds Preview on Page 1

Part XIII 2 Tax Return for Non-Resident's Investments in Canadian Mutual Funds 2026

Here's how it works

  • 01. Edit your form online

    Type text, add images, blackout confidential details, add comments, highlights and more.

  • 02. Sign it in a few clicks

    Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

  • 03. Share your form with others

    Send it via email, link, or fax. You can also download it, export it or print it out.

Definition & Meaning

The Part XIII.2 Tax Return for Non-Resident's Investments in Canadian Mutual Funds is a specific tax form used by non-residents of Canada who have investments in Canadian mutual funds. Its primary purpose is to report taxes owed on investment income earned from these funds. This form ensures compliance with Canadian tax laws and facilitates the transparent declaration of any income from such financial engagements.

  • Purpose: Designed to report and remit taxes on income generated from Canadian mutual funds.
  • Target Users: Non-residents with investments in Canadian financial products.
  • Compliance: Essential for legal adherence to Canada’s income tax regulations.

How to Use the Part XIII.2 Tax Return

Using the Part XIII.2 Tax Return involves a comprehensive understanding of your investment income and the associated tax obligations. This section aims to guide you through practical steps for effectively utilizing the form.

  1. Identify Income Sources: Gather all information related to income emanating from Canadian mutual funds.
  2. Calculate Tax Liability: Use Canadian tax codes relevant to non-residents to assess the tax due.
  3. Form Completion: Enter income details and corresponding tax calculations accurately on the tax return.
  4. Review and Adjust: Double-check for precision; ensure that all figures align with both Canadian and your home country tax regulations.
  5. Submit the Form: File the completed form with the Canadian tax authorities, observing the stipulated deadlines.

Practical Tips

  • Documentation: Keep detailed records of all income statements and tax documents.
  • Professional Assistance: For complex scenarios, consider consulting a cross-border tax expert.

Steps to Complete the Part XIII.2 Tax Return

Filing the Part XIII.2 Tax Return includes several distinct stages, each crucial for the correct submission of your tax obligations.

  1. Gather Required Information

    • Investment account statements.
    • Income reports from Canadian mutual funds.
  2. Calculate Total Income

    • Sum all income sources to determine your aggregate investment income.
  3. Determine Taxable Amount

    • Apply relevant exemptions or deductions as dictated by Canadian tax laws.
  4. Fill Out the Form

    • Accurately input calculated figures, ensuring all sections of the form are addressed.
  5. Verify Information

    • Cross-check figures to prevent errors that could lead to tax complications or audits.
  6. Submit and Retain Copies

    • Send the form to the designated Canadian tax authority.
    • Keep copies for your records and future reference.

Required Documents

Before beginning the filing process, it's essential to gather all necessary documentation to ensure a smooth and accurate submission.

  • Investment Statements: Documentation showing holdings and income from mutual funds.
  • Previous Tax Returns: Past submissions that might affect current filings.
  • Identification Details: Valid proof of identity and residency status for tax purposes.

Filing Deadlines / Important Dates

The timely submission of the Part XIII.2 Tax Return is critical to avoid penalties and ensure compliance.

  • Standard Filing Deadline: Generally aligns with the calendar year but confirm specific dates as they may vary.
  • Extension Possibilities: Check if extensions are possible due to special circumstances.
  • Penalties for Late Filing: Understand fees or interests accrued due to delays.

Who Typically Uses the Part XIII.2 Tax Return

Understanding who uses this tax form can provide context for its application and relevance.
  • Non-Resident Investors: Individuals residing outside of Canada with investments in its mutual funds.
  • International Businesses: Entities holding Canadian mutual fund portfolios.
  • Financial Advisors: Professionals managing portfolios for clients with international investments.
decoration imageratings of Dochub

Key Elements of the Part XIII.2 Tax Return

This section outlines the integral components of the form that users must be familiar with to ensure proper filing.

  • Income Reporting Section: Where income from each mutual fund is detailed.
  • Exemption Clauses: Relevant deductions or exemptions applicable to reported income.
  • Declaration and Signature: Legal section affirming the accuracy and honesty of the information provided.

Penalties for Non-Compliance

Understanding the repercussions for failing to adhere to filing requirements is crucial for non-resident investors.

  • Fines: Monetary penalties increase over time with persistent non-compliance.
  • Legal Action: In serious cases, legal proceedings could arise from fraudulent reporting.
  • Impact on Future Investments: Non-compliance could affect future investments or dealings in Canadian markets.

By following these comprehensive guidelines and detailed insights, individuals and businesses can effectively manage their legal obligations regarding non-resident investments in Canadian mutual funds.

be ready to get more

Complete this form in 5 minutes or less

Security and compliance

At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.

Related links

The Investment Funds Institute of Canada

Apr 15, 2015 2 Under our proposal, in preparing their U.S. tax returns, Canadian-resident U.S. taxpayers would use the interest, dividend, capital gains andRead more

Learn more
united states securities and exchange commission - form 10-k

Feb 17, 2017 The aggregate market value of common stock held by non-affiliates of the registrant as of June 30, 2016, the last business day of theRead more

Learn more
Tax Aspects of Technology Transfers between the United

by RD Brown 1986 Cited by 1 If the tax de- ducted under 105 exceeds the non-residents actual Canadian tax liability, it is refundable. For example, where the Canadian authorities.Read more

Learn more
If you believe that this page should be taken down, please follow our DMCA take down process here