

01. Edit your form online
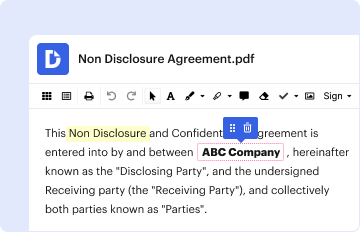
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
The 457(b) Plan Deferred Compensation is a retirement savings plan offered primarily to state and local government employees and certain non-profit organizations. This plan allows employees to defer a portion of their pre-tax income into the account, which grows tax-deferred until withdrawn, typically at retirement. This deferment reduces the employee’s taxable income for the year, providing potential tax savings.
To utilize the 457(b) plan effectively, participants must decide on the amount of salary they wish to defer each pay period, within IRS-imposed limits. Funds captured in the plan can be allocated across a range of investment options, such as mutual funds, stocks, or bonds. Participants have the flexibility to adjust their deferral amounts and investment choices as their financial goals change over time. Withdrawals, which are generally penalty-free, can be made at retirement or upon reaching the specified age, offering versatile retirement planning.
The IRS imposes specific rules on 457(b) plans, including contribution limits, eligible participants, and distribution regulations. The annual deferral limit is typically adjusted for inflation. Participants are required to follow these guidelines to ensure compliance and avoid penalties. The IRS allows withdrawals without penalties post-retirement, compared to other plans that might impose early withdrawal penalties.
When completing the 457(b) plan payout request form, participants must submit several essential documents:
Participants have multiple options for submitting the 457(b) plan deferred compensation payout request form:
The application process for 457(b) plan distributions involves completing the necessary forms with accurate information and submitting them through the preferred method. Approval time varies depending on the submission method and the complexity of the application. Generally, applicants can expect a decision within several weeks, with expedited processing available for online submissions.
Eligibility for participation in a 457(b) plan typically includes employees of state and local governments and certain non-profit organizations. Both full-time and part-time employees are eligible, though criteria may vary by employer. Employees must ensure that they comply with any organizational requirements or addendums to participate effectively in the plan.
We've got more versions of the 457(b) Plan Deferred Compensation form. Select the right 457(b) Plan Deferred Compensation version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Jan 26, 2017 Compensation generally includes amounts deferred at the employees election in the fol lowing employee benefit plans. Section 401(k) plans.
You are eligible to participate in the Duke 457(b) Deferred Compensation Plan if your annualized compensation equals or exceeds 150% of the Social Security
Plans eligible under 457(b) allow employees of sponsoring organizations to defer income taxation on retirement savings into future years.


