


01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
The "2014-7 form" refers to IRS Notice 2014-7, which addresses how qualified Medicaid waiver payments are treated for tax purposes. Under this notice, these payments are classified as difficulty of care payments, which are excluded from the gross income of employees living with the recipient of care. This exclusion helps alleviate the tax burden on caregivers who reside with the individuals they assist, ensuring they are not taxed on income meant to cover the increased costs of providing personal care in their household.
To utilize the provisions outlined in the 2014-7 form, caregivers must accurately report their income, ensuring that qualified Medicaid waiver payments are excluded from gross income on federal tax returns. This may involve submitting a certification statement to the relevant organization, such as Morning Star, which confirms the nature of the care provided and its compliance with the IRS guidelines. Caregivers should maintain thorough documentation and consult tax professionals to ensure correct application of this exclusion in their filings.
The 2014-7 form itself is an IRS notice, rather than a form to be filled out and submitted. Caregivers can access IRS Notice 2014-7 from the IRS website or through tax professionals who can provide guidance on its application. Understanding this notice requires familiarizing oneself with the qualifying criteria for Medicaid waiver payments to ensure correct interpretation and application during tax preparation.
The primary users of IRS Notice 2014-7 are caregivers who provide in-home services to individuals under Medicaid waiver programs. These caregivers often live with the individuals they care for, integrating personal and professional lives in a way that subjects their payments to specific tax treatments. The notice benefits self-employed caregivers, individual caregivers employed through agencies, and family members who provide care.
Consider a scenario where a caregiver named Jane, who lives with her sister under a Medicaid waiver program, receives monthly payments for providing care. Jane's payments qualify under IRS Notice 2014-7, allowing her to exclude them from her taxable income. By keeping detailed records and consulting with a tax professional, Jane ensures her taxes accurately reflect her eligible exclusions, reducing her financial liability during tax season. Another example involves a parent caring for an adult child with special needs, who also fits within the IRS guidelines, benefiting similarly from the notice's provisions.
Compliance with IRS Notice 2014-7 requires adhering to both the conditions outlined for medicaid waiver payments and accurate tax reporting. The notice represents a legal framework enabling caregivers to optimize their tax situation. By maintaining clear documentation and, where required, providing certification statements, caregivers uphold their responsibilities while benefiting legally from the exclusions provided under this IRS guidance.
We've got more versions of the 2014 7 form form. Select the right 2014 7 form version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2014 | 4 Satisfied (39 Votes) |
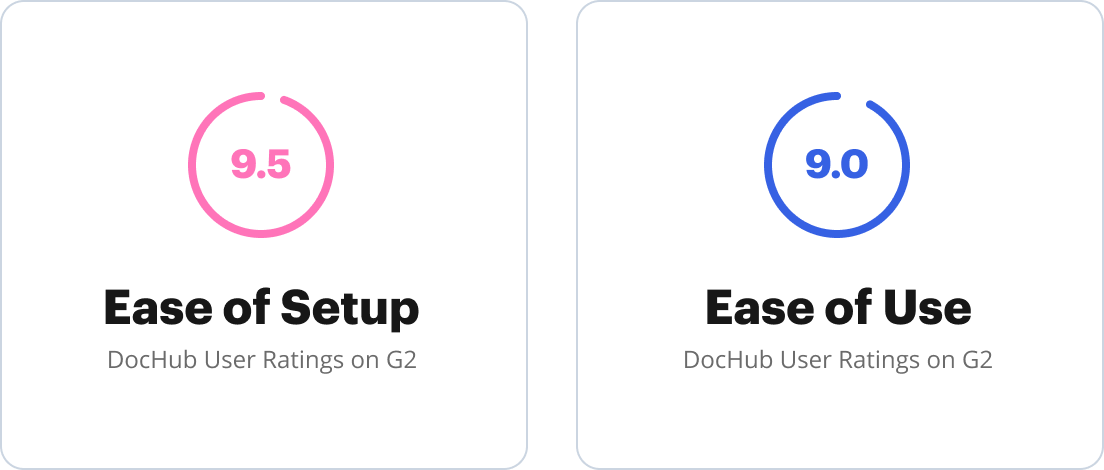
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
May 2, 2017 Notice 2014-7 provides that certain Medicaid waiver payments are excludable from income for federal income tax purposes. See Notice. 2014-7,Read more
IRS Notice 2014-7 allows certain Medicaid waiver payments to be excluded from income. Affected taxpayers may file amended returns.
Any individual who is not eligible to get a SSN but who must furnish a taxpayer identification number must apply for an ITIN on Form W-7.Read more


