


01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
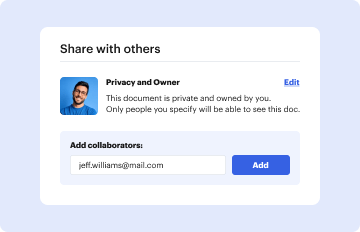
Send it via email, link, or fax. You can also download it, export it or print it out.
"2015 IRS Publication 6961" is an informative document authored by the Internal Revenue Service (IRS) that offers projections on the types and volumes of tax information and withholding documents in the United States. These projections assist in planning and operational activities within the IRS, outlining significant trends and expected changes based on legislative adjustments, past filing behaviors, and economic factors. It primarily targets entities managing their tax-related documentation.
Understanding and utilizing the 2015 IRS Publication 6961 effectively involves examining its tables and forecasts to prepare for upcoming tax filing cycles. Tax professionals and organizations can align their strategies with the anticipated trends in document submissions, impacting forms such as 1099s and adjustments anticipated in paper versus electronic filings. Adapting to these projections can aid in efficient resource allocation and policy formulation to meet filing deadlines and compliance mandates.
The publication is firmly rooted in the IRS's official guidelines, ensuring that taxpayers and entities aligned with its recommendations remain compliant with federal tax laws. Instructions provided help navigate complex filing seasons and adhere to necessary documentation requirements, minimizing the chances of errors that might lead to penalties.
Accountants, tax advisors, and financial planners often utilize this publication. The document aids these professionals in advising their clients, particularly businesses and large organizations, on preparing for document submissions. It also benefits IRS officials and policy-makers engaged in strategic planning and resource management throughout fiscal years.
Though the form itself is not completed like a tax return, engaging fully with its content involves several critical steps:
While 2015 IRS Publication 6961 itself doesn't need submitting, it guides on how anticipated tax documents should be handled:
Failing to adapt practices in line with the insights from the 2015 IRS Publication 6961, such as not meeting deadlines for submission or incorrect form filings, could lead to penalties. These may include fines and increased scrutiny from the IRS. Understanding and applying the knowledge from Publication 6961 can mitigate these risks by ensuring regulatory compliance and readiness in tax form submissions.
By focusing on these critical sections and related considerations, users of 2015 IRS Publication 6961 can strategize to remain compliant and efficient in handling their tax documents.
We've got more versions of the 2015 IRS Publication 6961 form. Select the right 2015 IRS Publication 6961 version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
This 2008 edition of IRS Document 6186, Calendar Year Return Projections for the United States and IRS Campuses, provides the most recent revisions to the.
Publication 6961 (revised 7-2015) is a product of the IRS Office of Research, within the Research, Analysis and Statistics organization. Janice M. Hedemann.
Feb 10, 2021 See the definitions of large accelerated filer, accelerated filer, smaller reporting company and emerging growth company in Rule 12b-2


