

01. Edit your form online
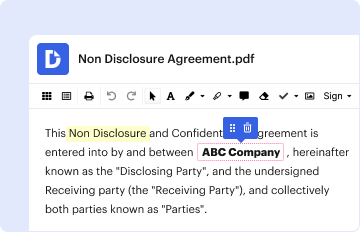
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
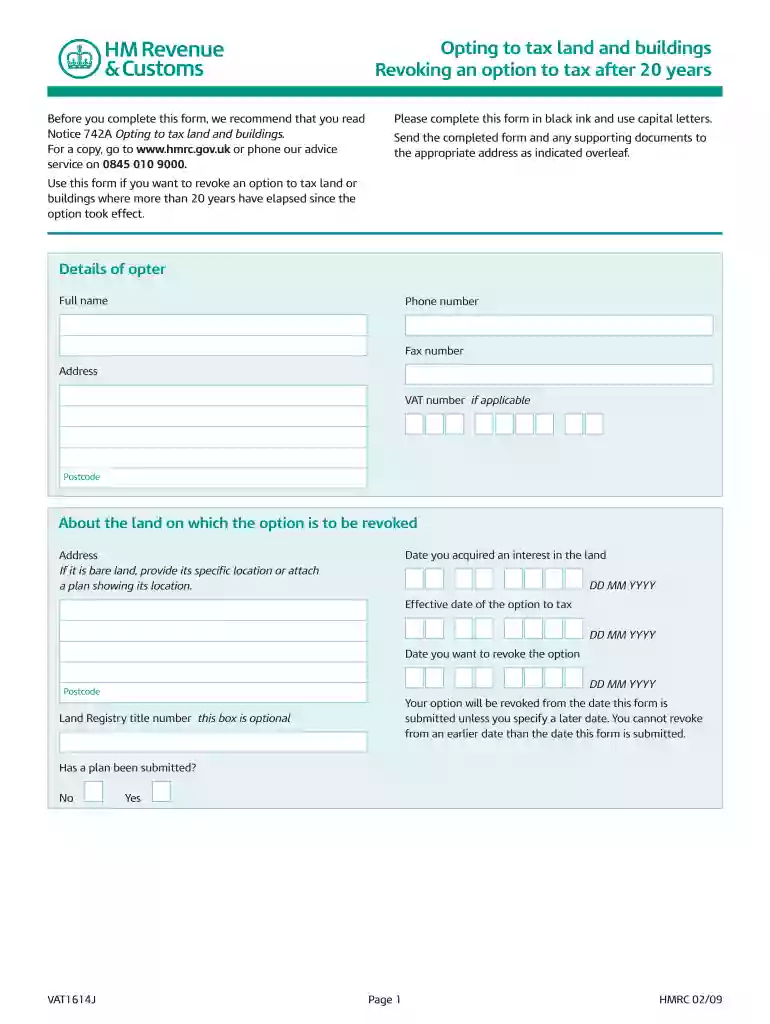
The VAT1614A V2 2009 Form is a document used to revoke an option to tax land and buildings after a 20-year period. This specific process is essential when businesses or individuals want to change their tax arrangements concerning properties. Opting to tax a property typically has implications on VAT recovery, so revocation allows for potential adjustments in VAT obligations. This form aligns with specific conditions set by HM Revenue & Customs, ensuring that all legal and procedural requirements are met.
There are several ways to obtain the VAT1614A V2 2009 Form, depending on your preference. Primarily, the form can be downloaded directly from the official HM Revenue & Customs (HMRC) website. Alternatively, you may request a paper copy by contacting HMRC via their helpline, ensuring you have all necessary details at hand to facilitate the process. The availability of digital formats allows for convenient access and ensures that you can start the revocation process without delay.
Completing the VAT1614A V2 2009 Form requires careful attention to detail. Here is a step-by-step guide:
Gather Information: Collect all necessary details about your property, including any previous tax options you have exercised.
Complete Required Sections: Use black ink to fill out each section, adhering strictly to the guidelines provided.
Declaration: Sign and date the declaration, affirming that all information provided is accurate and complete.
Additional Documentation: Attach any required supporting documents to substantiate your revocation request.
Review: Double-check all entered information to avoid errors that could delay processing.
Submission: Submit the form to the appropriate HMRC office or the Non-Established Taxable Persons Unit based on your location.
The VAT1614A V2 2009 Form is legally binding and must comply with regulations established by HM Revenue & Customs. Before submission, ensure that all applicable conditions for revocation are met. This includes a thorough understanding of how the revocation will impact your VAT liabilities and financial records. Compliance guarantees that the process is recognized and valid, avoiding potential legal issues or penalties.
Key elements of this form include detailed information about the property and the original option to tax. This encompasses:
Providing accurate responses to each section is essential for the successful processing of the form.
Businesses and individuals who have previously opted to tax a property, usually for VAT efficiency purposes, utilize the VAT1614A V2 2009 Form. This often includes:
The form must be completed and submitted within specific deadlines to avoid penalties. Revocation is only possible after the 20-year period following the initial tax option activation. Awareness of key dates is crucial for strategic financial planning and compliance with HMRC regulations.
For those using software like TurboTax or QuickBooks, compatibility with the VAT1614A V2 2009 Form typically involves manual data entry as these platforms may not directly support UK-specific forms. However, digital completion using PDF editing tools can facilitate ease of use and integration with existing financial software.
The submission of the VAT1614A V2 2009 Form requires certain accompanying documents to validate the revocation request:
Ensuring completeness of these documents supports a smooth processing experience and aids in the swift approval of the request.
We've got more versions of the vat1614a v2 2009 form form. Select the right vat1614a v2 2009 form version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.


