




01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
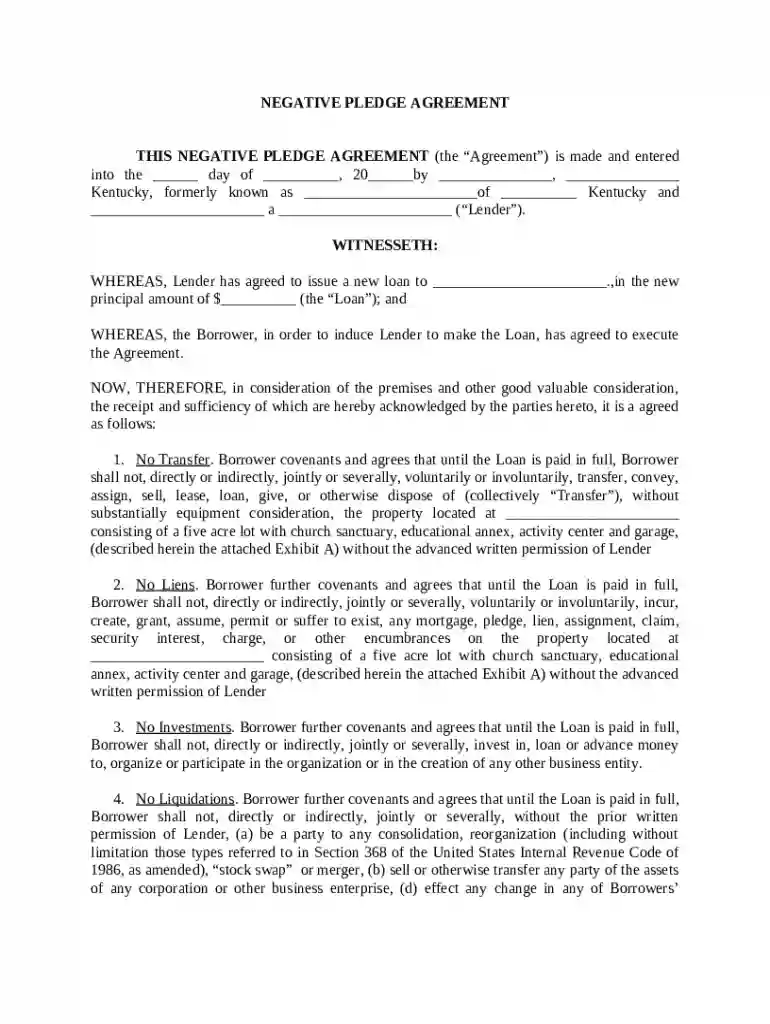
A Negative Pledge Agreement is a legal instrument between a borrower and a lender, which ensures that the borrower does not transfer, encumber, or dispose of specified assets until a loan is fully repaid. This agreement is crucial in the lending process as it prevents borrowers from jeopardizing the collateral that secures the lender's interests by taking on additional debts or liens. The agreement often includes covenants such as prohibitions on incurring new debts, making capital expenditures, or engaging in transactions that could affect the lender's security without obtaining prior consent from the lender. The essence of this agreement is to maintain the borrower's financial stability and protect the lender's interests.
The use of a Negative Pledge Agreement involves multiple steps to ensure both parties—lender and borrower—have a clear understanding of their obligations. Initially, the lender will draft the agreement to include specific covenants that the borrower must adhere to. These might involve restrictions on selling assets or taking additional loans that could undermine the lender's priority claim on the borrower's assets. After drafting, the parties review the document to negotiate terms, ensuring alignment with their respective interests. Once both sides agree to the conditions, the agreement is signed and becomes legally binding. The lender may routinely check that no violations occur, ensuring the borrower complies with all stipulations.
The core components of the Negative Pledge Agreement include:
Negative Pledge Agreements play a vital role in the legal landscape of lending. These agreements help secure a lender's interest without registering a security interest, allowing for flexibility in financial negotiations. They are enforceable under general contract law, and breach of terms can result in legal procedures where courts may grant the lender an injunction or damages. These agreements help lenders safeguard against potential risks by ensuring borrowers maintain asset integrity until debtor obligations are fulfilled.
Understanding specific terminology in the agreement is essential:
Consider a scenario where a corporation, "XYZ Corp.," seeks a substantial loan from "ABC Bank." To secure the loan, ABC Bank requires XYZ Corp. to sign a Negative Pledge Agreement. This agreement prevents XYZ Corp. from selling a substantial manufacturing plant, which serves as an informal form of collateral. Although there’s no formal lien, ABC Bank feels confident extending credit, knowing that the company's valuable assets are not at risk of being tied up in competing obligations.
While a Negative Pledge Agreement is a broad legal instrument, specific rules and enforceability can vary by state due to differences in commercial and contract law. Some states may have specific statutes governing the registration of such agreements or regarding how quickly a lender can move to secure interests in the event of a breach. It's critical to consult with a legal expert familiar with local regulations to ensure the agreement's enforceability and compliance with state-specific legal requirements.
Businesses undergoing rapid expansion or those involved in capital-intensive industries, such as manufacturing and real estate, often benefit from such agreements. By avoiding encumbrance of critical assets, these businesses maintain operational flexibility while still accessing necessary capital. Companies preferring not to surrender physical collateral can also choose this agreement to maintain business continuity without compromising asset liquidity.
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.



Apr 27, 2011 That includes a pledge of confidentiality that is not supported by authority established in statute or regulation, that is not supported
by CS Bjerret Cited by 119 However, negative pledge covenants in fact provide little protec- tion to unsecured lenders when the bdocHub is accompanied by dissipa- tion of assets. 15 The


