



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

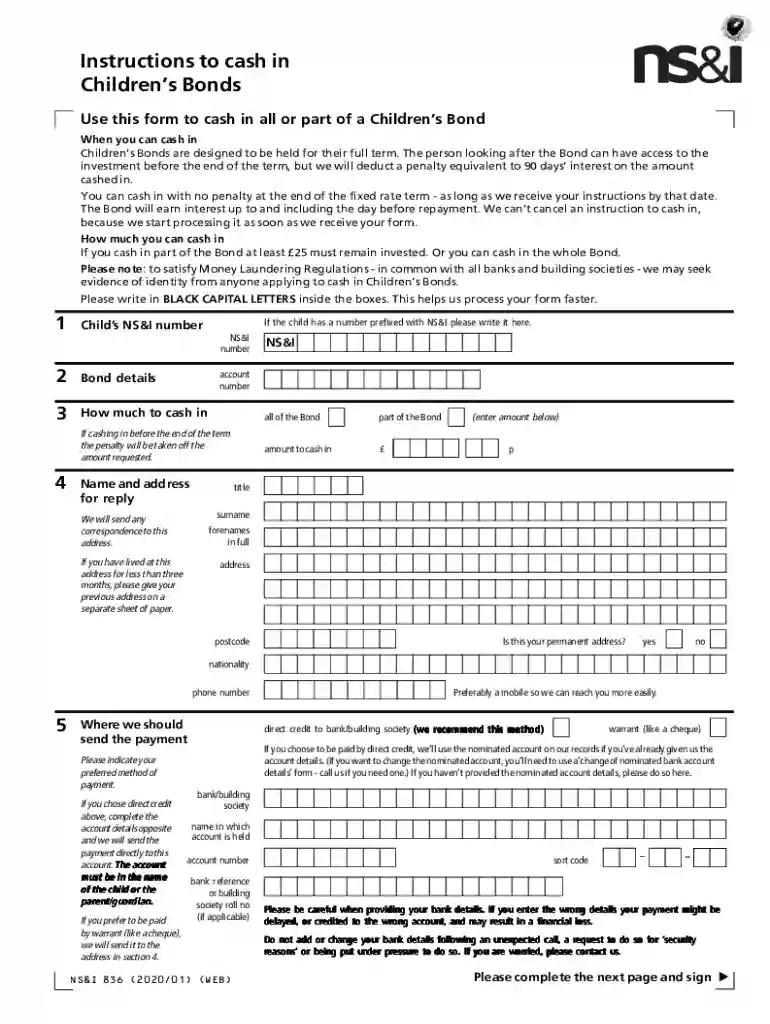
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
NSandI Children's Bonus Bonds were investment products offered by the National Savings and Investments (NSandI) in the UK. These bonds were designed as a tax-free savings option for children, allowing parents, guardians, or grandparents to invest a certain amount on behalf of a child. The bonds guaranteed a fixed rate of interest over a set period, making them an attractive choice for long-term savings aimed at benefiting children as they grow older. Originally, these bonds were intended to provide a secure and risk-free investment, distinguishing them from other financial products available for children's savings.
In recent years, significant changes have been made to NSandI Children's Bonus Bonds. One key change has been the discontinuation of new issues of these bonds. While existing bonds continue to accrue interest, no new investments can be made. This shift reflects a broader trend in the financial services sector, moving towards simplified savings products. For existing bondholders, the impacts include maintaining their current investments until maturity, with the option to reinvest in alternative NSandI products upon maturity.
Those holding NSandI Children's Bonus Bonds can continue to benefit from the set interest rates until maturity. It's crucial to keep track of maturity dates to decide the next steps for the investment. Current holders can choose to cash in the bonds upon maturity or reinvest in other available NSandI products, such as Premium Bonds or Investment Accounts. Understanding the original terms of the bond, including the interest rate and bonus conditions, is important for maximizing the investment’s full potential.
When it's time to cash in NSandI Children's Bonus Bonds, there are specific steps to follow to ensure the process is smooth and efficient:
Legally, NSandI Children's Bonus Bonds must be used in accordance with the terms and conditions set by NSandI. This includes adhering to the rules regarding ownership, transfer, and maturity. The bonds are intended for the benefit of the child, and when cashed in, the proceeds should be used for the child’s benefit, such as for educational expenses or other significant expenditures. It's critical to comply with tax regulations, ensuring that tax-free benefits are maintained under existing rules.
To originally purchase NSandI Children's Bonus Bonds, the principal eligibility requirement was that the beneficiary had to be a UK resident child under the age of 16. Bonds were purchased by an adult on behalf of the child, with the responsible adult managing the bond until the child came of age. Despite the discontinuation of new issues, these criteria are important for understanding legacy and implications for current holders.

Key features of these bonds include the fixed interest rate, the initial investment ceiling, and the maturity term, often lasting five years with a bonus payment at maturity if certain conditions were met. These elements made them a structured and predictable investment vehicle. Understanding these components helps current holders make informed decisions about future financial planning.
Understanding specific terms related to NSandI Children's Bonus Bonds is essential for making informed financial decisions:
These terms were vital in the original offering and remain important for managing existing bonds effectively.
We've got more versions of the Important changes to NSandI Childrens Bonus Bonds form. Select the right Important changes to NSandI Childrens Bonus Bonds version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.


