


01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
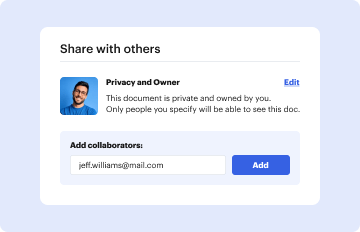
Send it via email, link, or fax. You can also download it, export it or print it out.
An Income Cap Trust, also known as a Miller Trust, is a financial arrangement used to qualify an individual for Medicaid benefits while managing their excess income. Designed for individuals with income over the eligibility limit for Medicaid, this irrevocable trust redirects excess income so that the individual can still qualify for benefits. By depositing enough income into the trust to bring the individual's income under Medicaid's cap, the trust ensures necessary healthcare support for those who might otherwise be ineligible. Typically, these trusts are established to manage the costs associated with long-term medical care, such as nursing homes or assisted living facilities, under Medicaid regulations.
To effectively use an Income Cap Trust, beneficiaries and their families need to understand its practical implementation. It involves setting up an irrevocable trust account in which the excess income is deposited each month. This process usually requires the assistance of an attorney familiar with Medicaid regulations to ensure compliance. Once the trust is established, the designated trustee manages the funds. These funds can only be used for the beneficiary's medical care and related services. The trustee's role includes ensuring timely deposits to keep the beneficiary within Medicaid eligibility limits and making approved expenditures from the funds as needed for qualifying expenses.
Obtaining an Income Cap Trust involves several steps. First, assess the need based on income levels and Medicaid requirements in the beneficiary's state. Next, consult with an elder law attorney who specializes in Medicaid planning. The attorney will draft a trust document that complies with state-specific guidelines. After the document is prepared, a bank account is often set up in the trust’s name. Once the account is active, the excess income is directed into the trust monthly. It’s crucial to select a trustee, who could be a family member or a professional, to manage the trust responsibly.
Income Cap Trusts are commonly used by individuals who have too much income to qualify for Medicaid but still need access to its benefits for long-term care expenses. This includes many elderly individuals who require nursing home care and cannot afford it without Medicaid assistance. Additionally, disabled persons whose income for a given month might temporarily disqualify them from Medicaid can benefit from this trust by maintaining consistent eligibility. Families seeking to ensure that their loved ones receive necessary medical support without depleting savings often turn to Income Cap Trusts as a solution.
The legal use of an Income Cap Trust is primarily to ensure compliance with Medicaid eligibility requirements. This involves adhering to federal and state-specific laws to structure the trust in such a way that it effectively bypasses income barriers without resorting to fraudulent practices. The trust must be managed with transparency, with the trustee maintaining accurate records of income flows and expenditures. Legal advisement is essential to ensure that the establishment and operation of the trust meet all necessary regulations and that any changes in Medicaid policy are reflected in the trust’s administration.
State-specific rules govern how Income Cap Trusts are utilized, particularly with regards to the income limits and structure of trust accounts. For example, some states dictate specific bank account structures or impose particular restrictions on how trust funds can be used. Additionally, differences in state policies determine how administrative fees and other trust-related costs are considered. Jurisdictions also vary in how they calculate spend-down amounts and handle resources. Therefore, consulting with a knowledgeable attorney about specific state requirements is crucial for setting up and maintaining compliance with a valid Income Cap Trust.
Consider a retiree whose pension and social security income exceed the local Medicaid eligibility threshold but who faces high healthcare costs due to necessary long-term care. An Income Cap Trust can be used to redirect the excess income above the threshold into the trust each month. A trustee would then manage these funds to pay for allowable expenses related to medical treatment and care providers, keeping the retiree within Medicaid eligibility limits.
Another scenario might involve a disabled individual who receives temporary or bonus income that exceeds Medicaid restrictions but is not representative of their base income level. By establishing an Income Cap Trust, this income can be routed to sustain Medicaid qualification, providing continuity in care services.
We've got more versions of the INCOME CAP TRUST form. Select the right INCOME CAP TRUST version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
IMPORTANT NOTES: The instructions accompanying this form must be followed. Complete all parts, checking the NONE box for each part where you have noRead more
An income cap trust (ICT) is a special type of trust. It allows someone with too much income to qualify for Medicaid long-term care services.


