



01. Edit your 199n e postcard online
Type text, add images, blackout confidential details, add comments, highlights and more.

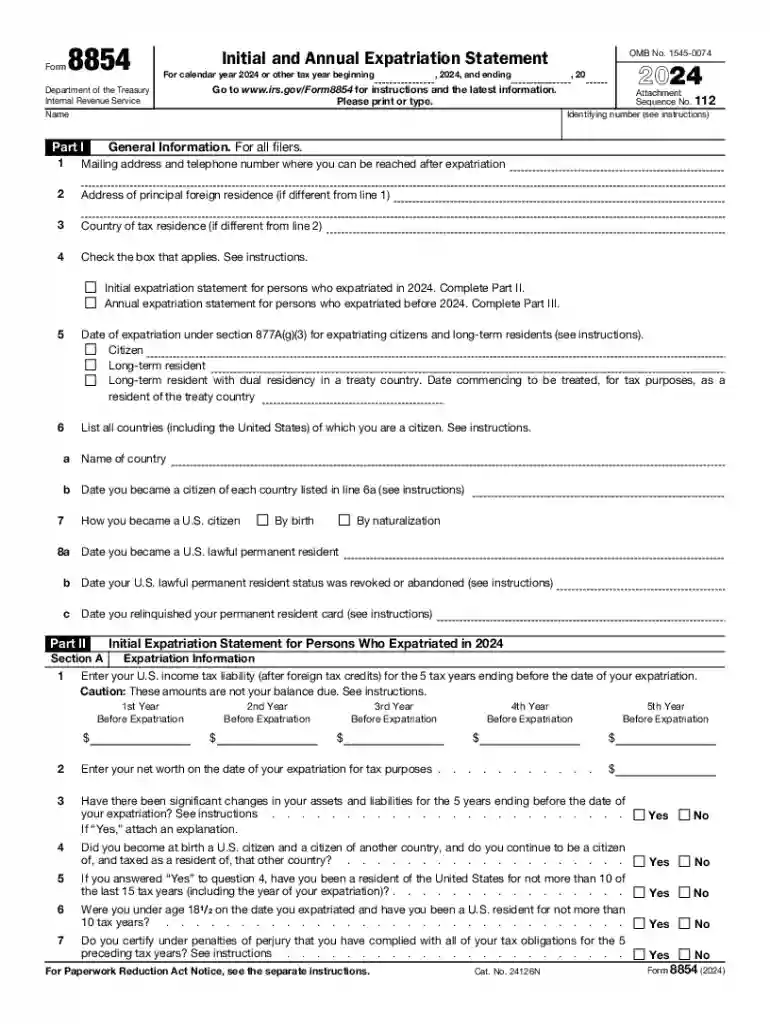
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send form 8854 via email, link, or fax. You can also download it, export it or print it out.
IRS Form 8854, known as the Initial and Annual Expatriation Statement, serves as a key document for individuals who are relinquishing their U.S. citizenship or terminating long-term residency. It assists the IRS in assessing an expatriate’s tax obligations under specific provisions of the Internal Revenue Code. The form not only helps determine if a person meets the criteria for being a “covered expatriate” but also captures vital financial information, ensuring compliance with tax reporting requirements during expatriation.
To ensure compliance with tax laws, only certain individuals are required to file Form 8854. Primarily, this includes anyone who has renounced their U.S. citizenship or whose long-term residency status has changed during the tax year. A “covered expatriate” is generally someone meeting specific criteria related to average annual net income tax for previous years, net worth thresholds, or failure to certify five years of tax compliance. Understanding these criteria is crucial, as different thresholds and conditions may impact filing requirements and tax liabilities.
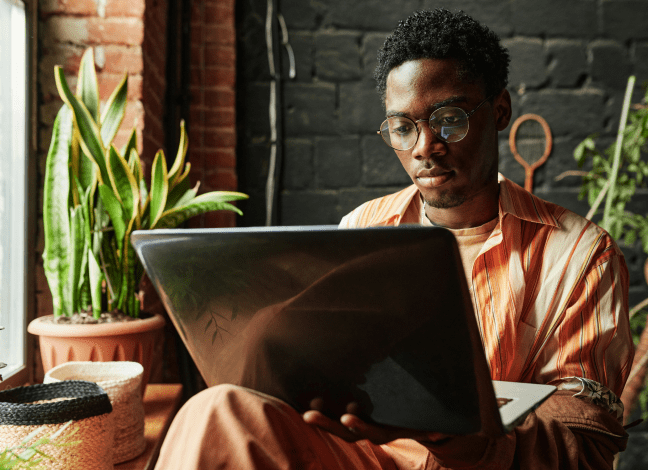

Obtaining Form 8854 can be done through various avenues to accommodate different preferences and needs. It is available for download directly from the IRS website, ensuring ease of access. Alternatively, taxpayers can request a physical copy by contacting the IRS directly. It’s important to check that the form version is current for the 2024 tax year, as outdated forms might not reflect recent changes in tax law or reporting requirements.
Completing Form 8854 requires careful attention to detail and knowledge of your financial position at expatriation. Here is a general step-by-step process:
The core components of Form 8854 consist of several sections that require precise information to ensure proper tax processing:
The IRS provides extensive guidelines to help expatriates understand their rights and responsibilities under tax laws. These guidelines detail the procedural norms for calculating tax liability upon expatriation and lay out the penalties for non-compliance, which could include substantial fines or an audit.
Meeting filing deadlines is critical in avoiding possible penalties. For those expatriating in the current year, Form 8854 must be filed with the individual's tax return for that year. It is crucial to stay informed about the annual due date for filing, generally falling on April 15th. Those requiring an extension should apply using Form 4868, noting that interest may accrue on any tax due during the extension period.
Failure to comply with Form 8854 filing requirements can lead to severe penalties:
Understanding these repercussions highlights the importance of timely and accurate completion and submission of Form 8854.
We've got more versions of the 199n e postcard form. Select the right 199n e postcard version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.1 Satisfied (39 Votes) | |
| 2024 | 4.8 Satisfied (47 Votes) | |
| 2023 | 4.6 Satisfied (25 Votes) | |
| 2022 | 4.1 Satisfied (29 Votes) | |
| 2021 | 4.8 Satisfied (86 Votes) | |
| 2020 | 4.4 Satisfied (198 Votes) | |
| 2019 | 4.3 Satisfied (40 Votes) | |
| 2018 | 4.4 Satisfied (87 Votes) | |
| 2017 | 4 Satisfied (45 Votes) | |
| 2016 | 4.4 Satisfied (49 Votes) | |
| 2015 | 4.2 Satisfied (60 Votes) | |
| 2014 | 4 Satisfied (41 Votes) | |
| 2013 | 4 Satisfied (55 Votes) | |
| 2012 | 4.1 Satisfied (31 Votes) | |
| 2011 | 4 Satisfied (35 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.

by L Snyder Cited by 23 IRS (via Form 8854) that they have complied with all U.S. federal tax obligations for the five years preceding the date of expatriation.339
Jan 13, 2016 For more information on the expatriation tax provisions, see Expatriation Tax the Instructions for Form 8854; and Notice 2009-85 (for


