



01. Edit your release of promissory note online
Type text, add images, blackout confidential details, add comments, highlights and more.

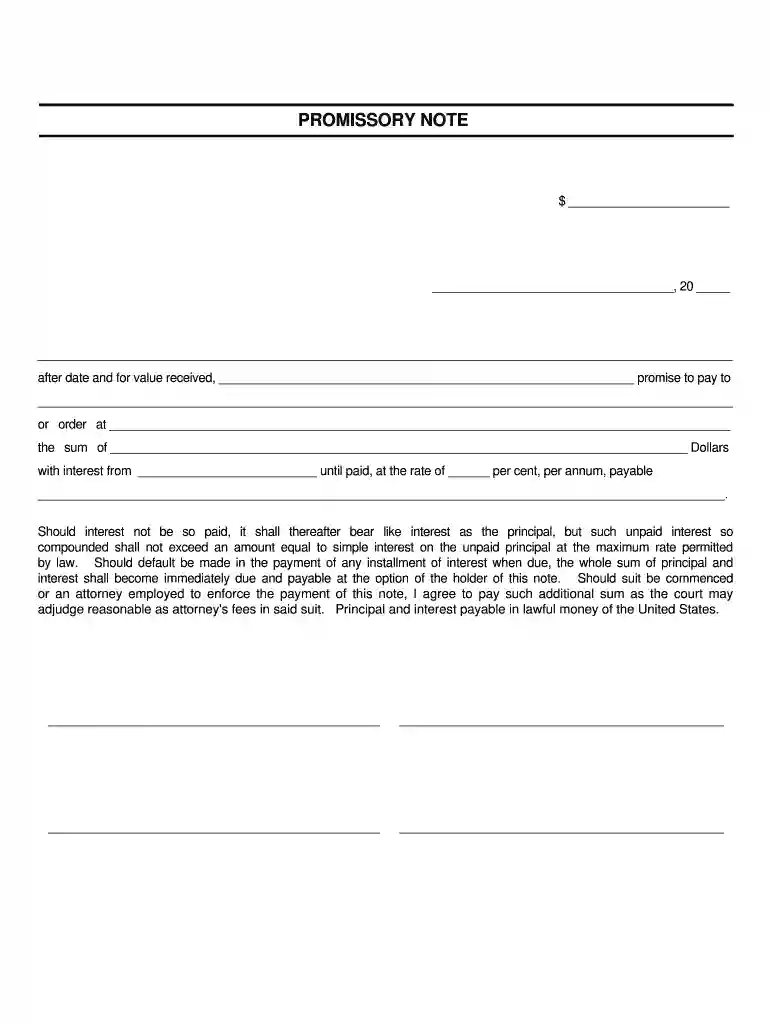
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send release of promissory note template via email, link, or fax. You can also download it, export it or print it out.
A "cap security instrument" typically refers to a financial document used in interest rate caps, which are contracts that limit the maximum interest rate payable on a variable-rate loan. These instruments are commonly employed in financial transactions to manage interest rate risk. In the context of a loan agreement, the cap security instrument represents an agreement between parties that establishes a ceiling for interest payments, ensuring that borrowers are not adversely affected by rising interest rates. The cap can be a crucial tool for borrowers who wish to maintain predictable payments and avoid unexpected rate increases.
Interest rate caps, represented through cap security instruments, are crucial in managing financial risks. They are commonly used in adjustable-rate mortgages (ARMs) and business loans. Borrowers use these instruments to protect against rising interest rates, securing financial stability. The cap security instrument details the cap rate, payment frequency, and term. When interest rates exceed this cap, the borrower is only responsible for payments up to the cap rate, with the lender or a third party covering any excess. Understanding these terms and conditions is essential for maximizing the benefits of the cap security instrument in loan agreements.
Obtaining a cap security instrument typically involves negotiating terms with lenders or financial institutions. Borrowers discuss desired interest rate limits and agreement terms with their lenders. Lenders then evaluate the borrower's credit profile and financial standing to determine eligibility. Should both parties agree, the borrower receives a contract outlining cap specifics such as rate limits and duration. Institutions may also require collateral or fees for providing these instruments. Consulting financial advisors can help borrowers navigate this process, ensuring the cap security instrument aligns with their financial goals and loan agreements.
Using a cap security instrument provides substantial benefits, especially for those with loans that have variable interest rates. It acts as insurance against rising interest rates, enabling borrowers to predict their future costs more accurately and manage their budget effectively. For businesses, capping interest rates helps maintain profitability by preventing costs from outpacing revenues due to rate spikes. Similarly, individuals with personal loans or mortgages can achieve financial stability without the burden of volatile interest payments. This instrument is an essential tool for anyone seeking risk mitigation in a fluctuating interest rate environment.
Cap security instruments are commonly used by commercial entities, real estate investors, and private individuals with variable-interest loans. Businesses with substantial debt exposure might use caps to stabilize cash flows and safeguard against unexpected rate increases. Real estate moguls employ these instruments when financing large projects that rely heavily on predictable loan repayments. Additionally, homeowners with adjustable-rate mortgages consider cap security instruments to protect themselves from future financial strain. These diverse users share the need to manage financial risk proactively by utilizing cap security instruments within their respective financial landscapes.

Cap security instruments hold legal significance by creating binding agreements between borrowers and lenders. Adhering to these contracts upholds borrowers' rights to capped interest payments, while lenders receive assurance of predetermined terms. In the U.S., these instruments must align with federal and state regulations governing financial contracts to remain enforceable. Failure to comply with legal stipulations can invalidate the instrument, leaving borrowers exposed to unprotected rate fluctuations. It is vital for users to ensure that cap security instruments are legally vetted and comply with applicable laws for the intended jurisdiction.
While federal guidelines provide a broad framework for the use of cap security instruments, each U.S. state may impose specific laws and regulations affecting their enforceability. States like California and New York have distinct interest rate-related consumer protection laws, potentially influencing the terms of cap security instruments. Users must familiarize themselves with these local legal nuances to ensure compliance. Consulting with legal professionals who understand state-specific regulations is advisable for both borrowers and lenders to avoid legal pitfalls and benefit fully from the cap security instrument.
We've got more versions of the release of promissory note form. Select the right release of promissory note version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2008 | 4 Satisfied (20 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.



Feb 25, 2009 The instrument is designed to give banks the incentive to replace USGprovided capital with private capital or to redeem the USG capital when.Read more
The MCP instrument is designed to give banks the incentive to redeem or replace the government-provided capital with private capital when feasible.


