


01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
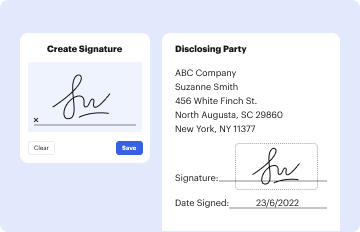
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
An Open-End Mortgage Deed is a legal document that establishes a secured interest in real estate property between a borrower and a lender. Unlike a traditional mortgage, the open-end mortgage allows the borrower to borrow additional funds beyond the original loan amount without needing to renegotiate the mortgage terms. The deed specifically defines important terms like 'Security Instrument,' 'Borrower,' 'Lender,' and 'Property,' detailing obligations related to payment, maintenance, and insurance.
In practical terms, this structure can benefit borrowers who need flexibility in accessing additional funds, commonly used for property improvements or expansions.
Utilizing an Open-End Mortgage Deed involves several critical considerations:
Initial Setup: Engage with a lender to establish the initial mortgage agreement, ensuring you meet all prerequisites for obtaining an open-end mortgage.
Borrowing Additional Funds: Once the mortgage is established, you can access additional funds by maintaining a good payment history and ensuring that your property's equity supports further borrowing.
Documentation and Compliance: It is essential to keep accurate records of all transactions and ensure compliance with local laws regarding open-end mortgages.
For example, if a homeowner initially borrows $200,000 to purchase a home and later decides to renovate the kitchen, they could borrow an additional $20,000 through the same mortgage deed.
The process for completing an Open-End Mortgage Deed is methodical and involves specific steps:
Pre-Approval: Obtain mortgage pre-approval to understand the borrowing limits and terms offered by the lender.
Property Valuation: An appraisal of the property determines its current market value, crucial for setting the borrowing limits of the open-end mortgage.
Legal Review: Legal consultation is advisable to understand the rights and obligations under the open-end mortgage terms.
Signing the Deed: Both borrower and lender sign the mortgage deed, making it legally binding and enforceable.
These steps ensure clear legal standing and protect both the borrower’s and lender's interests.
The Open-End Mortgage Deed contains several fundamental components, which include:
Payment Obligations: Detailed terms regarding the repayment schedule and interest rates.
Property Maintenance: Obligations relating to the upkeep of the property to maintain its value.
Escrow Provisions: Management of real estate taxes and home insurance through an escrow account.
Each element plays a role in protecting the lender's interest while providing clarity of obligations to the borrower.
The legal framework surrounding open-end mortgages is critical for both borrowers and lenders.
Compliance with State Laws: Laws governing open-end mortgages can vary significantly by state; thus, ensuring compliance with local regulations is paramount.
Enforcement in Default: Provisions included within the mortgage deed detail the lender's rights in the event of a borrower's default, such as foreclosure.
These legal uses ensure that the open-end mortgage serves its intended purpose without leading to undue financial risk.
Different states may have specific rules and regulations that affect the implementation and enforcement of an Open-End Mortgage Deed:
Interest Rate Regulations: Some states impose caps on interest rates that can be charged on open-end mortgages.
Recording Requirements: The deed must be recorded in the local county recorder's office to be enforceable.
State-Specific Provisions: Additional clauses may be required, depending on regional property and mortgage laws.
Understanding these state-specific rules ensures that the deed is both valid and enforceable under local jurisdiction.
Real-world scenarios illustrate the practical applications of open-end mortgages:
Home Improvement: Borrowers utilize additional funds for significant renovations, increasing property value and livability.
Unexpected Expenses: In instances of unforeseen financial burdens, homeowners can rely on the existing mortgage framework to address these costs without incurring new loan origination fees.
This flexibility makes the open-end mortgage a preferred choice for those with fluctuating financial needs.
Understanding key terms is essential for anyone involved with an Open-End Mortgage Deed:
Principal Amount: The initial sum borrowed under the mortgage agreement.
Equity: The difference between the property's market value and the outstanding mortgage balance.
Refinance: The process of renegotiating the mortgage terms, common when borrowers seek improved interest rates or loan conditions.
Each term carries implications for how the mortgage is managed and optimized over time. Understanding these helps in making informed decisions regarding mortgage management and financial planning.
We've got more versions of the OPEN-END MORTGAGE DEED form. Select the right OPEN-END MORTGAGE DEED version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2001 | 4 Satisfied (49 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.



Sec. 49-4b. Open-end mortgage as security for guaranty of an open-end loan. Mortgage deed requirements. Description of loan and secondary liability.Read more
by CB Hiester 1951 Cited by 5 The Architectural Forum has defined an open end mortgage as a mort- gage instrument which provides for additional advances at a later date, such advances to be


