

Here's how it works
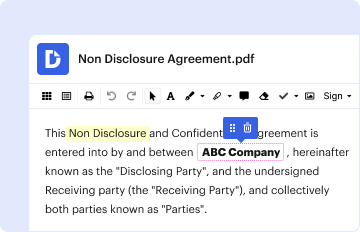
01. Edit your interest rate reduction refinancing loan online
Type text, add images, blackout confidential details, add comments, highlights and more.
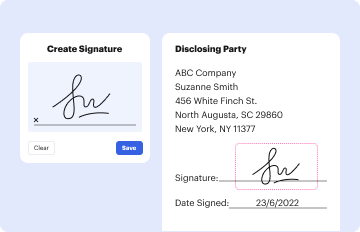
02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
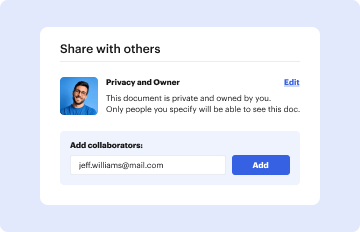
03. Share your form with others
Send va interest rate reduction refinancing loan via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out VA Form 26-8923. INTEREST RATE REDUCTION REFINANCING LOAN WORKSHEET with DocHub
- Click ‘Get Form’ to open the VA Form 26-8923 in our editor.
- Begin with Section I - Initial Computation. Enter the existing VA loan balance and any costs for energy-efficient improvements in Line 1.
- In Line 2, subtract any cash payment made by the veteran. This will help you calculate the total amount owed.
- Proceed to Line 3 and enter the total from Line 2. This is your starting point for further calculations.
- Continue filling out Section I by adding applicable percentages for discounts, origination fees, funding fees, and other allowable closing costs in Lines 5 through 9.
- Move to Section II - Preliminary Loan Amount. Here, input the amounts calculated from Section I to determine your preliminary loan amount.
- Finally, complete Section III - Final Computation by following the instructions to arrive at your maximum loan amount, ensuring all calculations are accurate.
Start using our platform today to easily fill out your VA Form 26-8923 for free!
Fill out VA Form 26-8923. INTEREST RATE REDUCTION REFINANCING LOAN WORKSHEET online
It's free
It's free
See more VA Form 26-8923. INTEREST RATE REDUCTION REFINANCING LOAN WORKSHEET versions
We've got more versions of the VA Form 26-8923. INTEREST RATE REDUCTION REFINANCING LOAN WORKSHEET form. Select the right VA Form 26-8923. INTEREST RATE REDUCTION REFINANCING LOAN WORKSHEET version from the list and start editing it straight away!
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
What is VA form 26 8923?
Abstract: VA Form 26-8923 is used to determine veterans eligible for an exception to pay a funding fee in connection with a VA-guaranteed loan.
What is a VA interest rate reduction refinance loan irrrl?
The Veterans Disability Compensation and Housing Benefits Amendments of 1980 introduced the IRRRL program to assist veterans who wished to take advantage of low interest rates to reduce their monthly payments. Income limits: There are no income limits on this program. Credit: No credit review is performed.
What are the rules for refinancing a VA loan?
Generally, you cant refinance until 210 days after the first mortgage payment was due, and you need to have made at least six monthly on-time payments. Seasoning guidelines for VA refinance loans can vary by lender, so ask your loan officer whether you qualify.
What are the cons of irrrl?
Cons of a VA streamline refinance You can only refi via a VA IRRRL if your new interest rate is lower than your current rate. You wont be able to take any cash out with the VA streamline refinance. Youll still have to pay a small funding fee. Your lender can still require documentation.
What is the current VA IRRRL rate?
He wants to take out a VA loan since they dont have a down payment for a house. Is that a good idea? DAVES RESPONSE: A VA home loan are one of the more expensive kinds of loans. Its a veterans benefit, but its not actually a benefit because you can get a conventional loan at less fees and lower interest rates.
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


People also ask
Is VA irrrl worth it?
With an IRRRL, you might qualify for a lower interest rate if one is available. This can mean paying less interest over your loans term, paying a lower monthly payment or both. Also, paying less can help you build equity in your home faster and shorten your repayment.