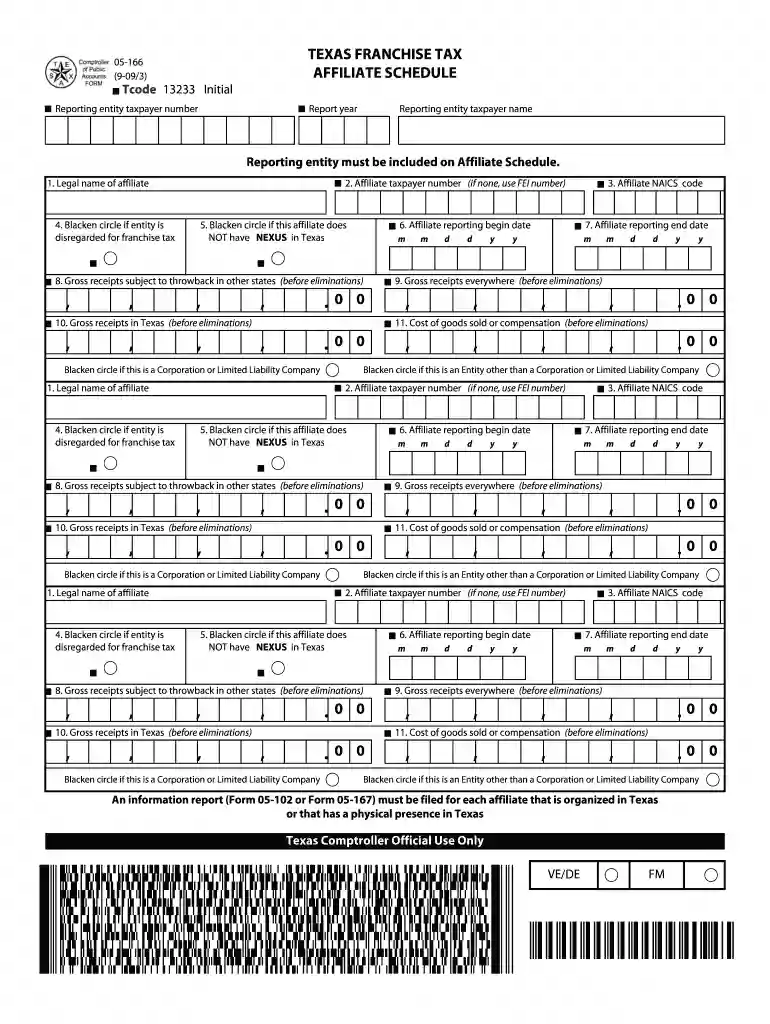
05 102 form 2022 Preview on Page 1

Form 05 166 affiliate schedule 2009-2026

Here's how it works

  • 01. Edit your 05 102 form 2022 online

    Type text, add images, blackout confidential details, add comments, highlights and more.

  • 02. Sign it in a few clicks

    Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

  • 03. Share your form with others

    Send it via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out form 05 166 affiliate schedule 2009 with our platform

Form edit decoration
9.5
Ease of Setup
DocHub User Ratings on G2
9.0
Ease of Use
DocHub User Ratings on G2
  1. Click ‘Get Form’ to open it in the editor.
  2. Begin by entering the 'Reporting entity taxpayer number' and 'Reporting entity taxpayer name' at the top of the form. Ensure these details are accurate as they identify your business.
  3. In section 1, provide the 'Legal name of affiliate'. This is crucial for proper identification of the affiliate entity.
  4. For section 2, input the 'Affiliate taxpayer number'. If none exists, use the FEI number instead.
  5. Fill in section 3 with the 'Affiliate NAICS code', which categorizes your business type.
  6. Complete sections 6 and 7 by entering the 'Affiliate reporting begin date' and 'Affiliate reporting end date'. Use the format mm/dd/yyyy for consistency.
  7. In sections 9 through 11, report financial figures such as 'Gross receipts everywhere', 'Gross receipts in Texas', and 'Cost of goods sold or compensation'. Ensure all amounts are entered correctly to avoid discrepancies.

Start using our platform today to fill out your form effortlessly and for free!

See more 05 102 form 2022 versions

We've got more versions of the 05 102 form 2022 form. Select the right 05 102 form 2022 version from the list and start editing it straight away!

VersionsForm popularityFillable & printable
20244.8 Satisfied (44 Votes)
20234.9 Satisfied (44 Votes)
20224.1 Satisfied (34 Votes)
20214.9 Satisfied (51 Votes)
20204.3 Satisfied (217 Votes)
20184.4 Satisfied (120 Votes)
20164.3 Satisfied (115 Votes)
20154.3 Satisfied (65 Votes)
20144.3 Satisfied (36 Votes)
20094 Satisfied (31 Votes)

be ready to get more

Complete this form in 5 minutes or less

Got questions?

We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.

Annual report and franchise tax. Texas requires LLCs to file a Franchise Tax Report and Public Information Report with the Comptroller of Public Accounts. These reports are due between January 1 and May 15. The fee is calculated based on margin.
Example: The taxpayer in this state sold merchandise to a purchaser in State A. Taxpayer is not taxable in State A. Upon direction of the taxpayer, the merchandise was shipped directly to the purchaser by the manufacturer in State B. If the taxpayer is taxable in State B, the sale is in State B.
0:42 3:09 As its accounting year begin date for its 2024 first annual franchise tax report the term expirationMoreAs its accounting year begin date for its 2024 first annual franchise tax report the term expiration date or the end of the accounting. Year is crucial for filing purposes. For an annual.
This is the throwback rule in which business activity is thrown back to Texas for apportionment purposes if the company is not subject to tax in the state in which they are making the sale.
Texas single member LLCs are not required to file an annual report but must submit an annual franchise tax report. Franchise taxes are based on net surplus and vary depending on the LLCs income.

Security and compliance

At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.

People also ask

In order to avoid the harsh throwback rules, the Department of Treasury and the IRS allows U.S. trust beneficiaries of a foreign trust to utilize the so-called default method. The default method of calculating distributions from a foreign nongrantor trust may, under certain circumstances, enable distributions of
The throwback tax applies when a trust that has accumulated income, all or some of which has not been taxed by California, makes a distribution of such accumulated income to a California- resident beneficiary who also was a California resident when the income was accumulated.
If you believe you are eligible to request a waiver, or if you have extenuating circumstances, complete Form 89-224, Request for Waiver of Penalty for Late Report and/or Payment (PDF), or Form 89-225, Request for Waiver of Penalty for Failure to File and/or Pay Electronically (PDF).

Related links

2009 Texas Franchise Tax Report Information and

Liability for the Tax. Each taxable entity identified on the Affiliate Schedule, Form. 05-166, is jointly and severally liable for the franchise taxRead more

Learn more
Fannie Mae Form 10-K for 2009 Annual Filing

by F Mae Securities registered pursuant to Section 12(g) of the Act: Variable Rate Non-Cumulative Preferred Stock, Series O, stated value $50 perRead more

Learn more
united states securities and exchange commission

Feb 28, 2026 Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. ☒ Yes ☐ No.Read more

Learn more
If you believe that this page should be taken down, please follow our DMCA take down process here