



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
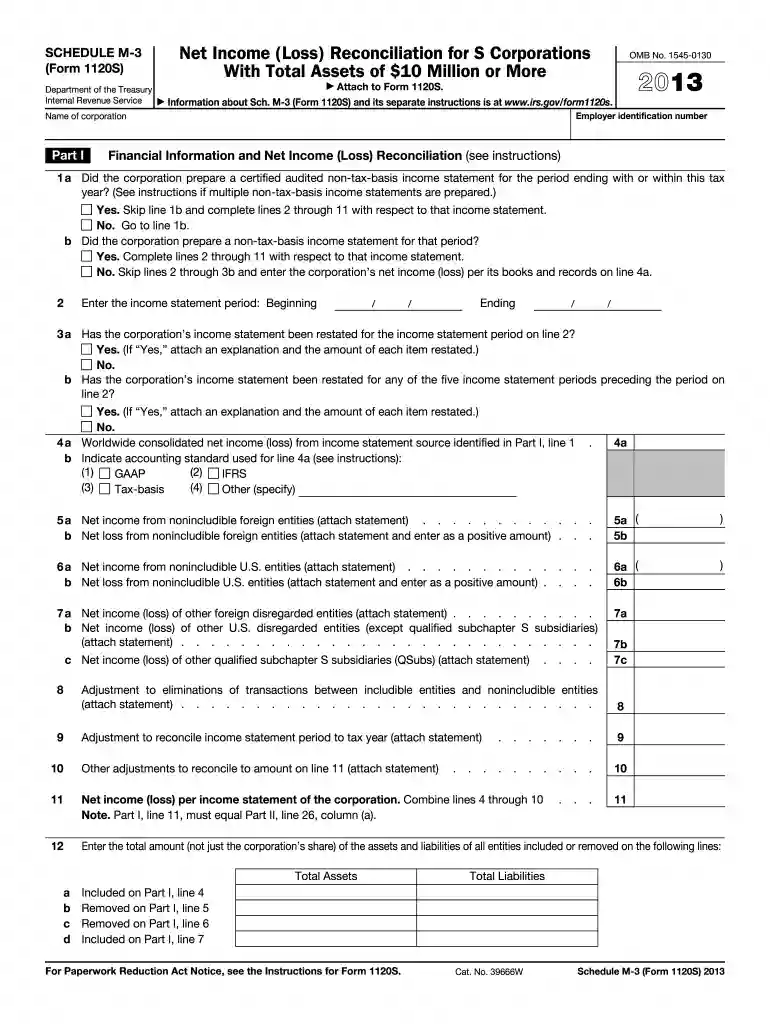
The 2013 Form 1120 S Schedule M-3 is a critical tax document for S Corporations with total assets of $10 million or more. It serves the purpose of reconciling net income (or loss) as reported in financial statements with the tax return figures. This form is designed to enhance transparency in financial reporting and ensure that discrepancies between book income and taxable income are explicitly addressed.
Understanding the main components of Schedule M-3 is crucial for proper completion and compliance:
The form is primarily used by large S Corporations based in the United States. These corporations are characterized by having assets of at least $10 million, requiring them to provide detailed reconciliations between financial statement income and tax return income for IRS scrutiny.

When preparing the Schedule M-3, gather the following documents:
According to the IRS guidelines, the Schedule M-3 provides a detailed framework for disclosure of book-tax differences. Corporations are required to identify and explain significant items that lead to these differences, ensuring accuracy and consistency in tax reporting.
Failure to accurately file the 2013 Form 1120 S Schedule M-3 can result in substantial penalties:
The 2013 Form 1120 S Schedule M-3 can be completed digitally or on paper:
We've got more versions of the 2013 Form 1120 S Schedule M-3.Net Income (Loss) Reconciliation for S Corporations With Total Assets of $10 Million or More form. Select the right 2013 Form 1120 S Schedule M-3.Net Income (Loss) Reconciliation for S Corporations With Total Assets of $10 Million or More version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Feb 6, 2020 3. CMS Energys maximum exposure to loss from these receivables is $10 million. The creditors of these partnerships do not have recourse toRead more
With Total Assets of $10 Million or More Part II Reconciliation of Net Income (Loss) per Income Statement of Includible Corporations With Taxable.Read more
disclosed by completing Schedule M-3, Net Income (Loss) Reconciliation for S Corporations With Total Assets of $10. Million or More. S corporations with lessRead more


