

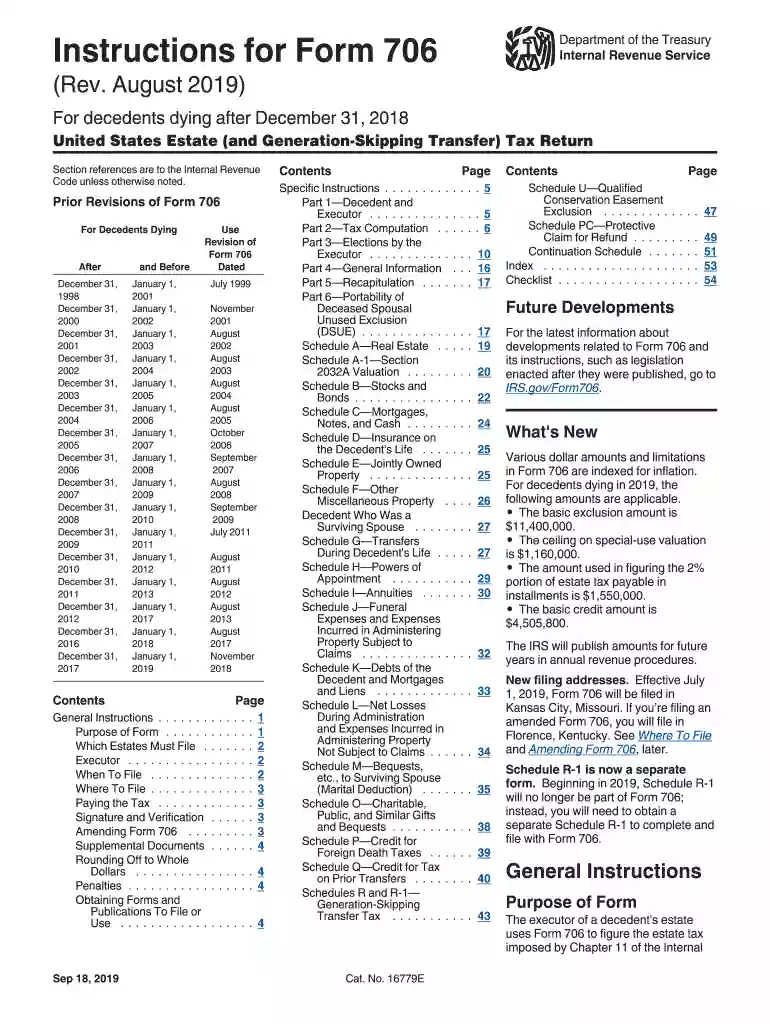
01. Edit your form 706 instructions online
Type text, add images, blackout confidential details, add comments, highlights and more.
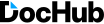
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send 706 instructions via email, link, or fax. You can also download it, export it or print it out.
Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return, serves to report estate and generation-skipping transfer taxes imposed on transfers at death. It applies primarily to estates of decedents who have died after December 31, 2018. This form is integral for estates exceeding the federal estate tax exemption threshold, ensuring proper tax computation and compliance with federal requirements. The form captures detailed financial information about the deceased's estate, including asset valuations, debts, and designated beneficiaries.
Gather Essential Documents: Begin by collecting relevant documents that detail the decedent’s financial interests, such as property deeds, bank statements, and investment account summaries.
Determine the Gross Estate Value: Calculate the total value of the decedent’s assets within the United States and abroad at the date of death. Include real estate, cash, stocks, and personal property.
Identify Deductions: List all permissible deductions, such as debts, funeral expenses, charitable contributions, and marital transfers, to potentially lower the estate’s taxable value.
Use Included Schedules: Accurately fill out required schedules that correspond to specific asset categories or deductions, such as Schedule A for Real Estate and Schedule J for Funeral Expenses.
Calculate Tentative Tax: Apply the current federal estate tax rates to determine the preliminary tax amount due, considering unified credits and any applicable exemptions.
Submit the Form: After review, submit Form 706 to the IRS along with required documentation, ensuring it is within nine months post the decedent's date of death, unless an extension is filed.
Executor Identification: Provide information on the executor responsible for managing the estate, including contact details and legal authority.
Asset Description and Valuation: Clearly describe each asset under the estate’s name, including appraisal reports or financial statements to support valuations.
Deductions and Credits: Outline eligible deductions and any credits applicable to the estate tax liability, which might include expenses and certain types of taxes paid.
Tax Payments and Installments: Explore options for paying tax liabilities, such as electing to pay in installments if the estate’s liquidity is constrained.
Alternate Valuation Date: Consider electing an alternate valuation date—six months after the date of death—if it results in a lesser estate tax burden.
Gross Estate: The total value of an individual’s property and financial assets at the time of death before liabilities and deductions.
Generation-Skipping Transfer (GST) Tax: A federal tax applied to transfers of property intended to skip a generation, such as a grandparent to grandchild.
Unified Credit: A tax credit that protects a certain value of an estate from tax—applicable at both the gift and estate tax levels.
Marital Deduction: An unlimited deduction allowed for bequests to a spouse, effectively deferring estate tax until the surviving spouse’s death.
Form 706 is utilized for legally reporting and paying estate taxes in compliance with U.S. federal tax laws, ensuring that executors fulfill their fiduciary responsibilities to the estate’s beneficiaries and government agencies. This requires accurate reporting of valuations, adherence to deadlines, and precise application of deductions as dictated by the IRS.
Original Filing Date: Executors must file the form within nine months of the decedent’s date of death.
Extension Requests: An automatic six-month filing extension can be requested to provide additional time for filing, though not for tax payment.
Payment Due Date: Tax payments are normally due by the original filing deadline unless an extension or payment installment arrangement is made.
While Form 706 is a federal mandate, states might impose their estate or inheritance taxes, with varying exemption limits and rates. Executors should consult state tax agencies to determine additional obligations and ensure full compliance. Local statutes potentially affect filing procedures and applicable deductions.
Failure to file Form 706 or to pay applicable taxes by the deadline can result in substantial penalties, including late filing fees and interest on unpaid taxes. The IRS may impose accuracy-related penalties for underpayment due to negligence or misreporting, highlighting the necessity of precise compliance with the instructions.
An estate valued at $15 million, composed of real estate, stocks, and personal property requires Form 706 to assess applicable estate taxes. Complex asset allocations necessitate detailed appraisals and valuation documentation for each category.
If the decedent’s will includes contributions to qualified charitable organizations, detailed calculations must be furnished to enable significant reductions in the taxable estate value via charitable deductions on Form 706.
We've got more versions of the form 706 instructions form. Select the right form 706 instructions version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.8 Satisfied (21 Votes) | |
| 2024 | 4.3 Satisfied (20 Votes) | |
| 2023 | 4.6 Satisfied (58 Votes) | |
| 2022 | 4.2 Satisfied (29 Votes) | |
| 2021 | 4.8 Satisfied (110 Votes) | |
| 2020 | 4.3 Satisfied (140 Votes) | |
| 2019 | 4.4 Satisfied (169 Votes) | |
| 2018 | 4.2 Satisfied (109 Votes) | |
| 2017 | 4 Satisfied (55 Votes) | |
| 2016 | 4.3 Satisfied (75 Votes) | |
| 2015 | 4.4 Satisfied (63 Votes) | |
| 1999 | 4 Satisfied (38 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
If you are filing this form solely to elect allocation. See the instructions for Line 5 property, whether tangible or intangible,.Read more
When To File. Generally, the trustee must file Copy. A of Form 706-GS(D-1) with the IRS and send Copy B to the distributee.Read more
Sep 11, 2025 The executor of a decedents estate uses Form 706 to figure the estate tax imposed by chapter 11 of the Internal Revenue. Code. This tax isRead more


