



01. Edit your 1042 s instructions online
Type text, add images, blackout confidential details, add comments, highlights and more.

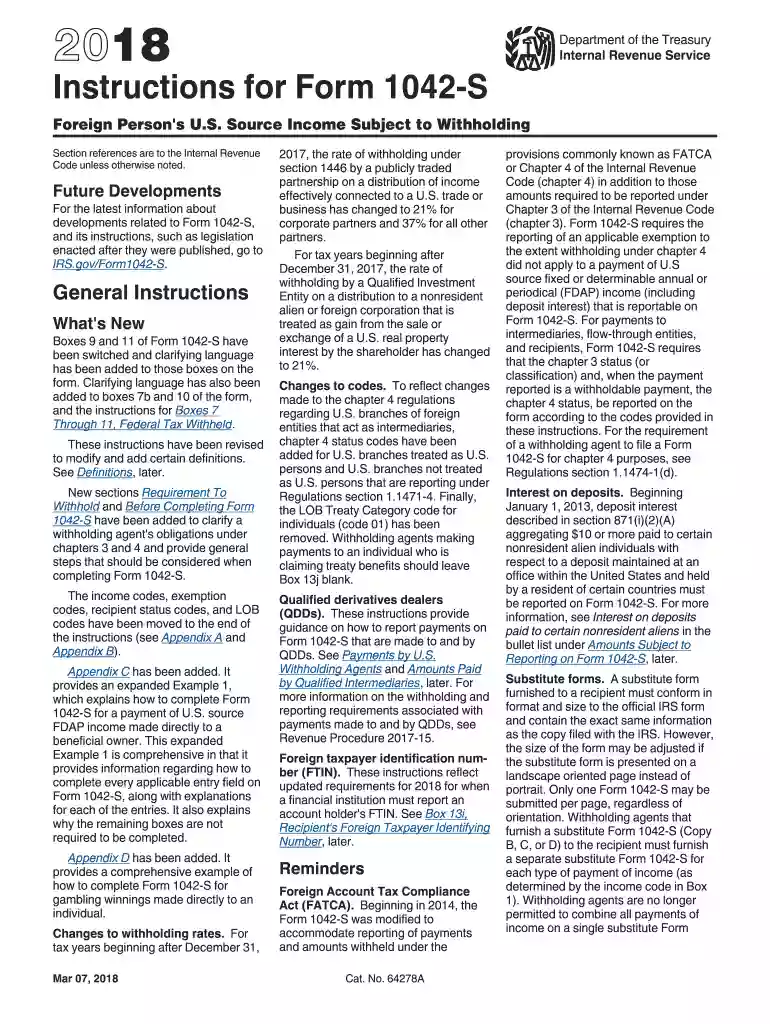
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
Form 1042-S is a critical document used to report U.S. source income paid to foreign individuals and entities that is subject to withholding tax. This form is essential for compliance with federal tax regulations to ensure income is correctly reported and taxes are accurately withheld. It serves as a communication tool between the Internal Revenue Service (IRS) and taxpayers, providing a detailed account of income types and amounts paid and the taxes withheld on them.
Incorrect or incomplete Form 1042-S submissions can lead to penalties and interest charges. Accurate filing ensures both the payer (withholding agent) and the payee (income recipient) fulfill their tax obligations, maintaining compliance with U.S. federal tax laws.
The instructions provide a comprehensive list of income codes that denote different types of income subject to reporting. Exemption codes are equally significant as they specify conditions under which income may be exempt from withholding taxes.
Understanding the roles in this process is crucial. Withholding agents must ensure all income subject to withholding is reported correctly. They are responsible for filing the form with the IRS and providing copies to income recipients.
The appendices in the instructions offer illustrative examples and further explanation of codes, facilitating better understanding and accurate usage. These examples help clarify complex situations, easing the preparation process.
Gather Required Documents: Before starting, collect necessary forms, such as copies of prior filings, payee information, and any applicable agreements that affect tax reporting.
Understand Income and Exemption Codes: Review the codes to ensure accurate categorization of income and any applicable exemptions.
Enter Payer and Payee Information: Accurately input the necessary details including tax identification numbers and address information.
Report Income and Withholding: Complete the sections detailing specific income types and amounts withheld, ensuring they match supporting documentation.
Complete Contact Information Section: Provide accurate contact details for both the payer and payee to facilitate effective communication should issues arise.
Review and Submit: Before submission, review the form for accuracy and completeness. Submissions can typically be made electronically or via mail, depending on availability and preference.
Form 1042-S must be filed with the IRS and provided to foreign recipients by March 15 each year. This deadline is crucial to avoid non-compliance penalties and ensure foreign recipients can timely report their income.
Extensions might be available under specific circumstances, allowing for additional time to gather necessary information and ensure accuracy in filing.
Failure to file Form 1042-S accurately and timely can result in substantial penalties. These can include:
Efforts should be made to keep detailed and accurate records, regularly review IRS guidelines for updates, and possibly consult with tax professionals to minimize the risk of errors.

Entities responsible for paying U.S. source income to foreign individuals or companies, such as corporations, partnerships, fiduciaries, and certain government agencies, act as withholding agents.
Individuals and entities receiving U.S. sourced income subject to withholding use this form to report income and tax withheld when filing their tax returns, as required by their home country's tax regulations.
Withholding agents are obligated to withhold taxes on qualifying payments and report these accurately using Form 1042-S. They must keep thorough records to support reported amounts.
The IRS routinely updates regulations surrounding international income reporting. Staying informed through the IRS website or tax publications ensures compliance with current rules and provides guidance on form changes directly from the source.
For detailed withholding guidelines, withholding agents may refer to IRS Publication 515, "Withholding of Tax on Nonresident Aliens and Foreign Entities," which provides comprehensive instructions for withholding requirements and obligations.
These examples demonstrate the critical role of Form 1042-S in various types of income transactions with foreign entities, emphasizing correct use as fundamental to maintaining compliance with U.S. tax law.
We've got more versions of the 1042 s instructions form. Select the right 1042 s instructions version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.3 Satisfied (22 Votes) | |
| 2024 | 4.7 Satisfied (37 Votes) | |
| 2023 | 4.6 Satisfied (41 Votes) | |
| 2022 | 4.8 Satisfied (155 Votes) | |
| 2020 | 4.4 Satisfied (187 Votes) | |
| 2019 | 4.3 Satisfied (88 Votes) | |
| 2018 | 4.2 Satisfied (88 Votes) | |
| 2017 | 4.2 Satisfied (72 Votes) | |
| 2016 | 4.4 Satisfied (545 Votes) | |
| 2015 | 4.3 Satisfied (67 Votes) | |
| 2013 | 4 Satisfied (29 Votes) | |
| 2012 | 4 Satisfied (25 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Nov 14, 2018 Form 1042-S (Foreign Persons US Source Income Subject to Withholding) is created for anyone considered a nonresident alien for US tax purposes.Read more
Your request must be in writing and received within 60 days of the date you receive the letter containing our decision. You can call us and ask for the appealRead more
Mar 7, 2018 With respect to a withholdable payment, the recipient copy should be provided to the intermediary or flow-through entity named as a recipient.Read more


