

Here's how it works
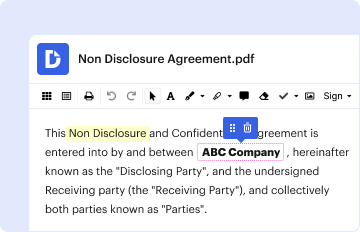
01. Edit your employer owned life insurance online
Type text, add images, blackout confidential details, add comments, highlights and more.
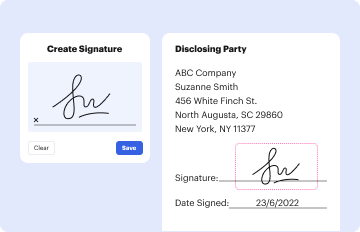
02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
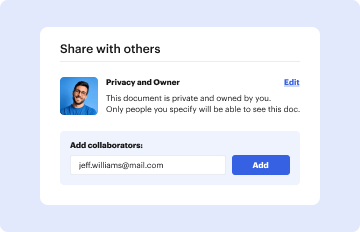
03. Share your form with others
Send it via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out Employer Owned Life Insurance - Notice and Consent Form.PDF with our platform
- Click ‘Get Form’ to open it in the editor.
- Begin by entering the maximum face amount for which the Employee will be insured in the designated field. This is crucial for clarity regarding coverage.
- In the 'Employee's Consent' section, ensure that the Employee reads and understands all terms. They must acknowledge their consent by signing and dating the form.
- The Employer should also sign and date the form in their respective section, confirming their intent to purchase and own the insurance policy.
- Review all entries for accuracy before finalizing. Utilize our platform’s features to save or share the completed document as needed.
Start using our platform today to effortlessly complete your Employer Owned Life Insurance forms online, for free!
Fill out Employer Owned Life Insurance - Notice and Consent Form.PDF online
It's free
It's free
See more Employer Owned Life Insurance - Notice and Consent Form.PDF versions
We've got more versions of the Employer Owned Life Insurance - Notice and Consent Form.PDF form. Select the right Employer Owned Life Insurance - Notice and Consent Form.PDF version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2007 | 4.8 Satisfied (55 Votes) |
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
Can I get life insurance on my dad without his permission?
Purchasing Life Insurance for your Parents will require the consent of your parents. Without them agreeing to the policy, you would not have any insurable interest unless you have been designated their power of attorney or some other form of legal guardianship.
Who must file form 8925?
For Paperwork Reduction Act Notice, see instructions. Generally, every policyholder owning one or more employer-owned life insurance contracts issued after August 17, 2006, must file Form 8925 for each tax year the contract(s) is owned.
What happens to life insurance through an employer?
Employer-provided life insurance policies typically terminate once you leave the employer. However, some policies may be portable after you leave your job, letting you pay for the same coverage via a renewable term life policy.
What is the IRS form for employer-owned life insurance?
Reporting Requirements. The IRS has released Form 8925 that is required to be filed by employers (with their income tax return) that own employer-owned life insurance contracts. The form itself contains the instructions. The form asks if the employer has a valid consent form for each covered employee.
Do you need consent for life insurance?
To get a life insurance policy for someone else, you need to first prove insurable interest. After you have proven that you have an insurable interest, you need to show that you have consent from the person you are trying to insure.
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


People also ask
Which type of life insurance beneficiary requires consent?
If youre the owner of a life insurance policy with a revocable beneficiary, you can change the beneficiary of your policy without consent from the current beneficiary. On the other hand, a policy with an irrevocable beneficiary requires the policyholder to get the current beneficiarys consent before making a change.
Can I get life insurance on my husband without him signing?
You cant take out a policy on just anyone. You need to have the individuals permission (you cant get a policy on someone without them knowing), and you must be able to show insurable interest -- proof that you will suffer financially if they die.
Can you get life insurance on someone without their consent?
However, you cant buy a plan for anyone without an insurable interest and consent from the person you are buying life insurance for. Insurable interest is present when you can prove to an insurance provider that it would be financially harmful to you if the person you aim to take a policy out for passes away.