



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
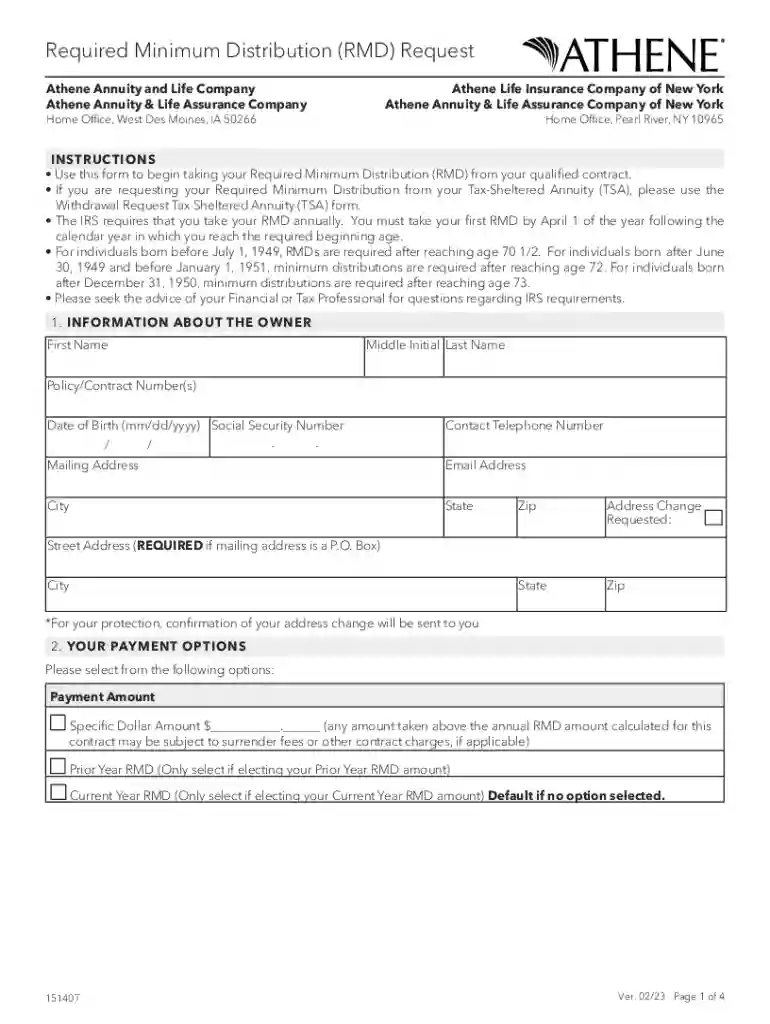
The Required Minimum Distribution (RMD) Form is a critical document used primarily by individuals who own certain retirement accounts in the United States. As mandated by the Internal Revenue Service (IRS), it ensures that individuals withdraw a minimum amount from their tax-deferred retirement accounts annually once they reach a certain age. The purpose is to ensure that taxes are eventually paid on these retirement savings. The RMD is applicable to accounts like Traditional IRAs, 401(k)s, 403(b)s, and other similar retirement plans. This form helps streamline the process by capturing essential details such as the account holder's personal information, the account type, and the withdrawal amount.
To correctly use the RMD Form, individuals must first determine the amount they are required to withdraw based on their age and the balance of their retirement accounts at the end of the preceding year. The form captures these calculations, and users must input details such as the type of retirement account and the withdrawal method. It's crucial to follow the specific instructions on the form to avoid penalties. Once filled out, the form serves as an official record of the distribution decision and can be submitted or retained for record-keeping.
Completing the RMD Form involves several precise steps to ensure compliance. Start by gathering all necessary documents, such as previous year's account statements. Next, accurately fill out sections requiring personal information, such as your name, social security number, and account details. Carefully calculate and enter the RMD amount, ensuring alignment with IRS guidelines. Finally, choose your preferred payment option for the distribution, be it a direct deposit or a check, and submit the form to the appropriate entity, often your retirement plan administrator.
The RMD Form is pivotal for tax compliance and retirement planning for individuals with significant retirement savings. By correctly completing and filing this form, you not only avoid possible IRS penalties for non-compliance but also strategize your withdrawals in a manner that aligns with your tax planning. This form also serves as a valuable financial record, helping you track your retirement distribution decisions over time.
Understanding the terminology associated with the RMD Form is essential for proper handling. Key terms include:
IRS guidelines provide the foundation for RMD calculations and filings. According to these guidelines, RMDs must start by April 1 of the year following the year you turn 73. Account holders are required to continue distributions annually thereafter. The IRS provides life expectancy tables used to determine the correct withdrawal amounts, ensuring that individuals receive consistent guidance accepted nationwide.
Being aware of the relevant deadlines is critical to avoid penalties. For most individuals, RMDs must be taken by December 31 each year. However, the first distribution can be delayed until April 1 of the year following the year you reach 73. Missing these deadlines can result in a hefty penalty, equivalent to 50% of the amount that should have been withdrawn.
Failing to comply with RMD requirements can lead to severe financial consequences. If the minimum distribution is not taken by the deadline, the IRS imposes a significant penalty of 50% of the amount that should have been distributed. Correctly filling out and submitting the RMD Form is essential to avoid these costly penalties and ensure that your retirement strategies remain legally compliant.
We've got more versions of the Required Minimum Distribution (RMD) Form form. Select the right Required Minimum Distribution (RMD) Form version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.


