



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
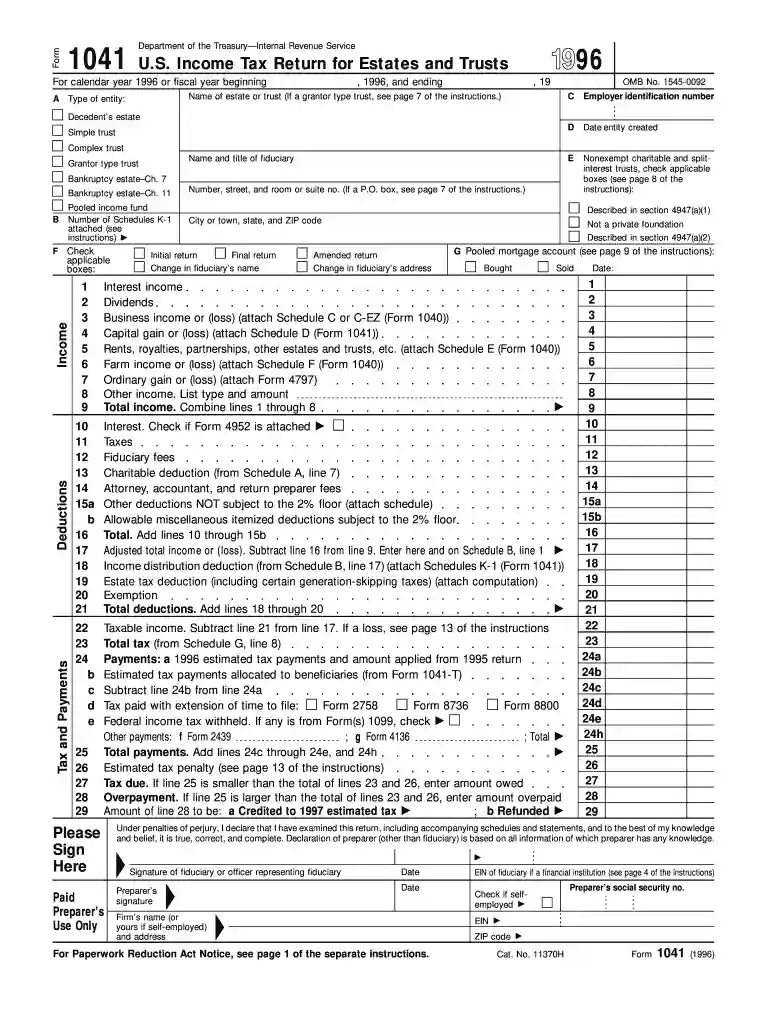
Form 1041 is the U.S. Income Tax Return for Estates and Trusts, a critical document used for reporting the income, deductions, and tax liabilities of estates and trusts for the tax year 1996. This form is essential for fiduciaries managing estates and trusts to comply with IRS requirements, ensuring transparency and accountability in declaring financial activities. The form includes sections for income such as dividends, capital gains, deductions like charitable donations, and calculations of taxable income and tax due. Understanding Form 1041 is crucial for accurate tax filing and compliance.
To efficiently utilize the IRS Form 1041 for 1996, follow a methodical process:
Gather Necessary Information: Collect all relevant income records, including interest, dividends, rental income, and any other sources of income related to the estate or trust.
Complete Income Sections: Accurately fill in details pertaining to the income the estate or trust received during the year. This includes specifying any gains from securities or properties.
Identify Allowable Deductions: Determine deductions applicable to the estate or trust, such as administrative expenses, distributions to beneficiaries, and charitable contributions.
Calculate Taxable Income: Subtract total deductions from total income to determine the taxable income of the estate or trust.
Compute the Tax: Use tax tables or applicable rates for 1996 to calculate the tax liability based on the calculated taxable income.
These steps provide a structured approach to completing the form, ensuring accurate reporting and compliance.
Several critical elements are pivotal in preparing IRS Form 1041 correctly:
Understanding and accurately filling each of these components ensures precise compliance and prevents errors leading to potential fines.
The legal obligations surrounding the IRS Form 1041 rely heavily on correct usage and compliance:
Strict compliance ensures legal protection and accountability under U.S. tax law, reinforcing the fiduciary’s role in estate and trust management.
Completing the form involves following detailed steps for accuracy:
Prepare Form: Use the correct 1996 version of Form 1041.
Enter Basic Information: Fill out the identification section with the estate or trust’s details.
Document Income Sources: List all income received, such as dividends, interest, and other income.
Capture Deductions: Input permissible deductions, ensuring all claimed deductions have proper supporting documentation.
Finalize Section Totals: Review and verify each section to ensure mathematical accuracy and compliance. Ensure totals are accurately computed across sections for consistency.
Review Fiduciary Details: Ensure the fiduciary signs and dates the document, affirming the accuracy and completeness of the information.
This step-by-step guide ensures fiduciaries complete the form efficiently, reducing errors and potential compliance issues.
Several documents are necessary for accurately completing Form 1041:
These documents support the information entered into Form 1041, ensuring all claims are validated.
Adhering to the filing deadlines is crucial to avoid penalties:
Maintaining awareness of these timelines is vital for fiduciaries managing estates or trusts in 1996 to ensure compliance and avoid unnecessary penalties.
Failure to submit Form 1041 timely and accurately can result in significant complications:
Ensuring timely and accurate submissions will mitigate these risks, promoting a smooth tax filing process and preserving the financial health of the estate or trust.
We've got more versions of the irs form 1041 for 1996 form. Select the right irs form 1041 for 1996 version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.4 Satisfied (30 Votes) | |
| 2024 | 4.5 Satisfied (37 Votes) | |
| 2023 | 4.7 Satisfied (20 Votes) | |
| 2022 | 4.6 Satisfied (50 Votes) | |
| 2021 | 4.9 Satisfied (46 Votes) | |
| 2020 | 4.2 Satisfied (46 Votes) | |
| 2019 | 4.4 Satisfied (92 Votes) | |
| 2018 | 4.2 Satisfied (95 Votes) | |
| 2017 | 4.4 Satisfied (262 Votes) | |
| 2016 | 4.3 Satisfied (72 Votes) | |
| 2015 | 4.3 Satisfied (57 Votes) | |
| 2014 | 4 Satisfied (38 Votes) | |
| 2013 | 4.2 Satisfied (73 Votes) | |
| 2012 | 4 Satisfied (33 Votes) | |
| 2011 | 4.3 Satisfied (71 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Feb 4, 2021 Securities registered pursuant to Section 12(g) of the Act: None. Indicate by check mark if the Registrant is a well-known seasoned issuer,Read more
However, a trust in existence on August. 20, 1996, that was treated as a domestic trust under prior law, may continue to file as a domestic trust for tax years.Read more
96. Page 2. Form 1041 (1996). Page 2. Charitable Deduction. Do not complete for a simple trust or a pooled income fund. 1. Amounts paid for charitable purposesRead more


