


01. Edit your ny form 2024 online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send ny 2024 form via email, link, or fax. You can also download it, export it or print it out.
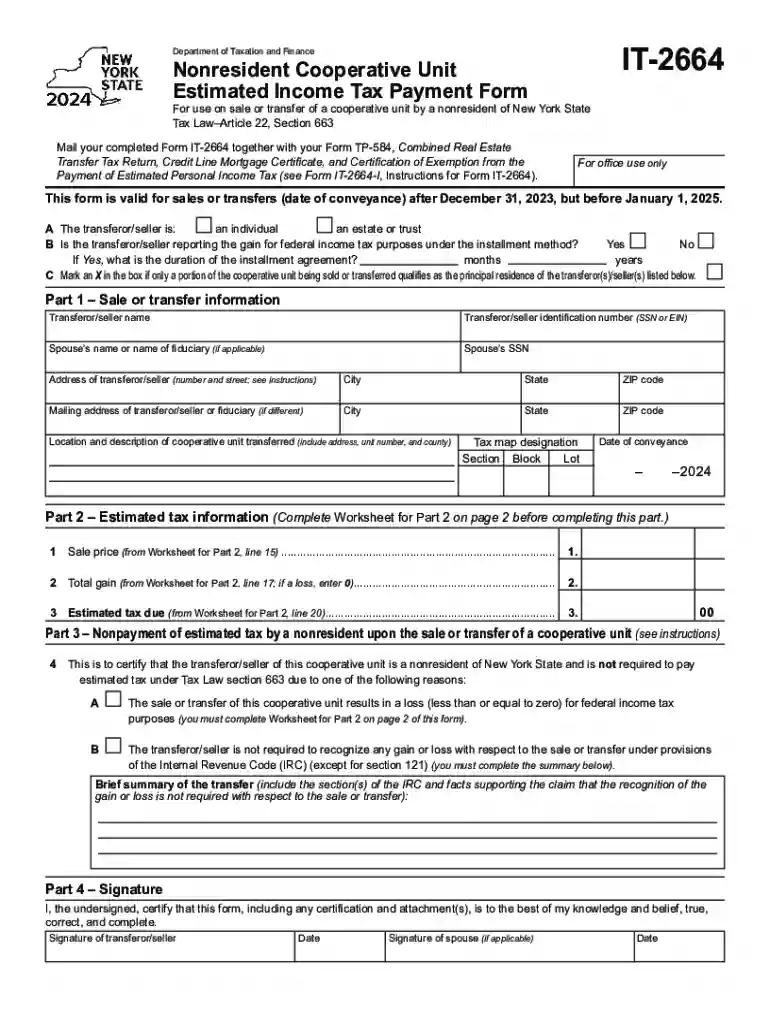
The Form IT-2664 is a critical document for nonresidents of New York State engaged in the sale or transfer of a cooperative unit. This Estimated Income Tax Payment Form is specifically designed for transactions occurring from December 31, 2023, through January 1, 2025. The form ensures that nonresidents accurately report and remit the estimated income tax due on the gains from such real estate transactions. The primary function of this form is to facilitate the collection of taxes owed to the state for these specific types of sales by nonresidents, effectively bridging the gap between the occurrence of a taxable event and the subsequent tax payment requirement.
Understanding the elements within Form IT-2664 is essential for accurate completion. The form requires vital information such as:
Accurate completion of Form IT-2664 requires careful attention to detail. Here's a structured approach:
Timeliness in submitting Form IT-2664 is crucial to avoid penalties. The form, along with the estimated tax payment, must be submitted simultaneously with the property transfer. For transactions falling within the specified window of December 31, 2023, to January 1, 2025, ensuring submission in alignment with these dates is imperative to remain compliant with New York State tax regulations.
Form IT-2664 can be accessed through several avenues:
Submission methods for Form IT-2664 include:
The primary users of Form IT-2664 are nonresident individuals or entities involved in the sale or transfer of cooperative units in New York State. This includes:
Fulfilling the requirements of Form IT-2664 is mandatory, as non-compliance can lead to significant penalties:
Understanding and adhering to these elements ensures compliance with New York State tax regulations and mitigates financial or legal risks.
We've got more versions of the ny form 2024 form. Select the right ny form 2024 version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.2 Satisfied (60 Votes) | |
| 2024 | 4.3 Satisfied (21 Votes) | |
| 2023 | 4.9 Satisfied (58 Votes) | |
| 2022 | 4.8 Satisfied (35 Votes) | |
| 2021 | 4.4 Satisfied (102 Votes) | |
| 2020 | 4.3 Satisfied (49 Votes) | |
| 2019 | 4.3 Satisfied (338 Votes) | |
| 2018 | 4 Satisfied (52 Votes) | |
| 2016 | 4.4 Satisfied (162 Votes) | |
| 2015 | 4 Satisfied (28 Votes) | |
| 2014 | 4 Satisfied (46 Votes) | |
| 2011 | 4 Satisfied (44 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.


Jan 16, 2026 IT-2664-I (Instructions) Nonresident Cooperative Unit Estimated Income Tax Payment Form - valid for sales or transfers (date of conveyance)
May 18, 2010 The total of annual estimated tax payments and withholding tax must be at least 90% of the tax liability for the current year or 100% of tax


