




01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
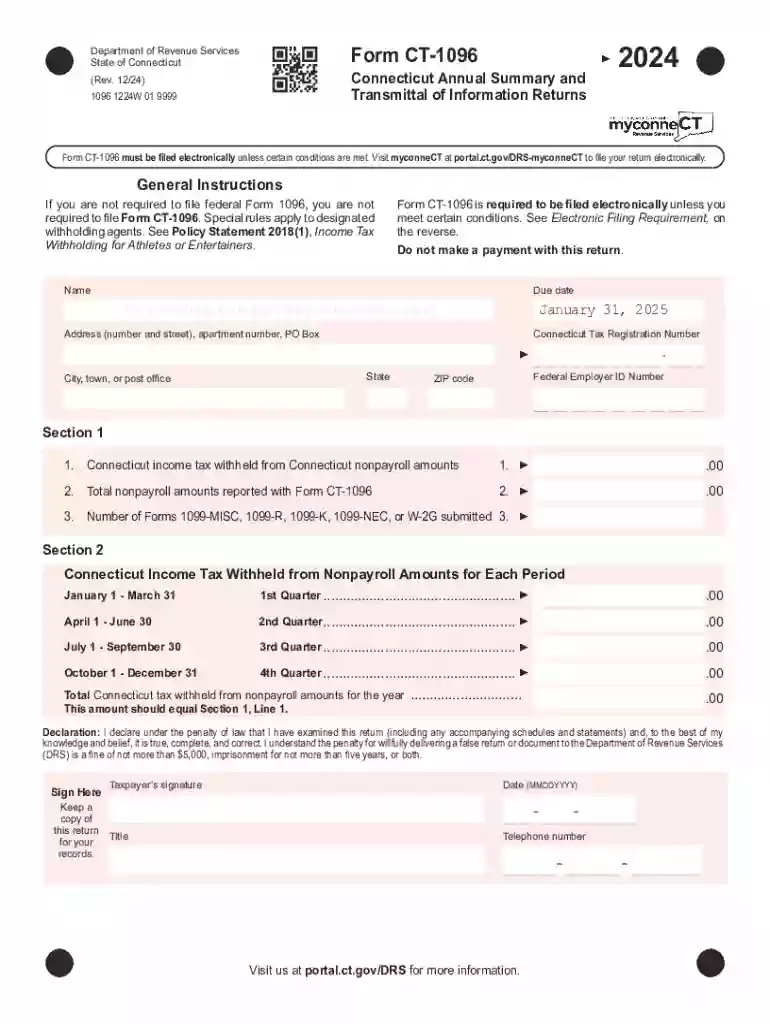
Connecticut Form CT-1096, known as the Annual Summary and Transmittal of Information Returns, is utilized for reporting state income tax withheld from nonpayroll amounts. It corresponds with the federal Form 1096 but is specific to Connecticut. This form must be filed by entities that have previously submitted federal Form 1096. The primary intent is to provide a comprehensive summary of all accompanying tax forms pertaining to nonpayroll transactions within the state. By submitting this form, businesses convey a complete annual picture of their tax obligations concerning nonpayroll activities, ensuring compliance with Connecticut tax regulations.
To effectively complete the Connecticut Form CT-1096, first gather all relevant nonpayroll tax forms, such as 1099-MISC, associated with the entity’s transactions for the year. Begin by closely following the provided instructions, which detail how to consolidate these forms into a singular annual summary. Ensure accuracy by cross-referencing with financial records and payroll data. Special attention should be paid to the electronic filing requirements unless the filer qualifies for a waiver. Each step of the process transforms raw financial data into a structured tax summary for state submission.
Connecticut Form CT-1096 must be filed by January 31 each year for the preceding tax year. This deadline aligns with the federal submission timelines for Form 1096, ensuring consistency in tax reporting across both federal and state levels. It is crucial to meet this deadline to avoid penalties for late submission. For entities unable to comply with the electronic filing requirement, a waiver must be applied for before the deadline to be considered for alternative filing methods.
Failure to submit Connecticut Form CT-1096 on time or providing inaccurate information can result in financial penalties. These may include fines for late submission and additional charges for each erroneous form. The Connecticut Department of Revenue Services stipulates that businesses maintain meticulous records to support data reported in CT-1096, thereby minimizing error risks. Ensuring full compliance not only avoids penalties but also facilitates smooth audits and fiscal assessments by the state.
Key documents required for Connecticut Form CT-1096 completion include all information returns, such as 1099 forms, reflecting nonpayroll amounts paid during the year. Additionally, records substantiating Connecticut income tax withheld from these payments must be available. Meticulous organization of these documents is essential to ensure accuracy and completeness of data transcribed onto the CT-1096 form. A checklist including payer information, recipient details, and withholding amounts can streamline form preparation.
The preferred method for filing Connecticut Form CT-1096 is electronic submission through the state's official platform, ensuring timely processing and confirmation of receipt. In certain circumstances where electronic filing is not feasible, businesses may apply for a waiver to submit physical copies by mail. In-person submission is generally not common for this form type due to administrative efficiency aimed through digital channels. Providing accurate contact information ensures any follow-up or clarification needs from state tax authorities are swiftly addressed.
We've got more versions of the Connecticut Form CT-1096 Annual Summary Instructions form. Select the right Connecticut Form CT-1096 Annual Summary Instructions version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.1 Satisfied (36 Votes) | |
| 2024 | 4.9 Satisfied (28 Votes) | |
| 2022 | 4.2 Satisfied (32 Votes) | |
| 2021 | 4.7 Satisfied (92 Votes) | |
| 2020 | 4.2 Satisfied (28 Votes) | |
| 2019 | 4 Satisfied (27 Votes) | |
| 2018 | 4.3 Satisfied (147 Votes) | |
| 2017 | 4.4 Satisfied (68 Votes) | |
| 2016 | 4.4 Satisfied (631 Votes) | |
| 2015 | 4 Satisfied (40 Votes) | |
| 2015 | 4.1 Satisfied (44 Votes) | |
| 2014 | 4 Satisfied (54 Votes) | |
| 2012 | 4 Satisfied (29 Votes) | |
| 2011 | 4 Satisfied (57 Votes) | |
| 2009 | 4 Satisfied (59 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Line 1: Enter the total amount of income tax withheld from. Connecticut nonpayroll amounts subject to Connecticut income tax withholding during the calendarRead more
On or before the fifteenth day of March following the end of each calendar year, the designated withholding agent must complete Form CT-1096 ATHEN and file it,.Read more


