

01. Edit your form online
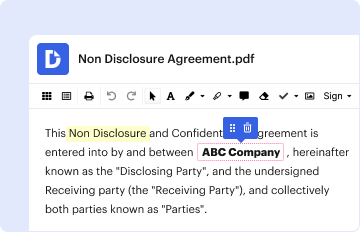
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
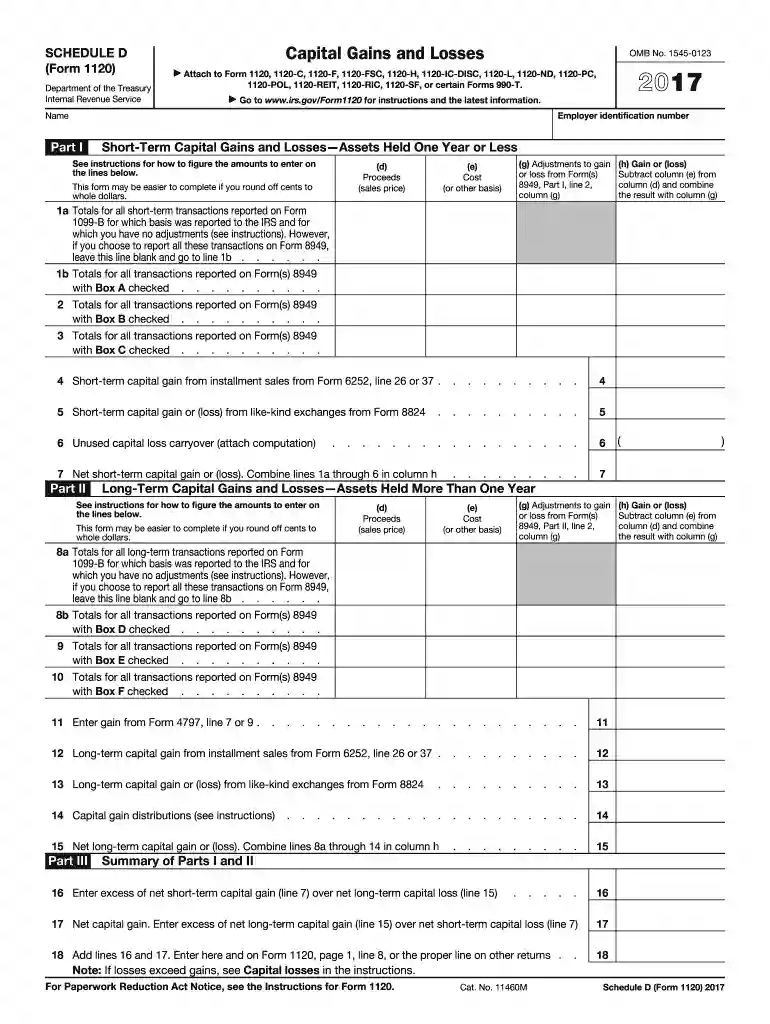
Form Losses 2017, officially known for its role in detailing capital losses, serves a critical function in the financial landscape. Primarily used by individuals and businesses to report capital losses incurred during the sale of assets, this form allows taxpayers to account for and calculate the impact of these financial transactions on their overall taxable income. Recognizing short-term versus long-term capital losses is central to its purpose, as each has distinct tax implications. Short-term losses stem from assets held for under a year, while long-term losses pertain to assets held for more than a year. Accurately distinguishing these losses is necessary to ensure compliance with tax regulations and to optimize potential tax savings.
Acquiring Form Losses 2017 is a straightforward process. The form can be downloaded directly from the Internal Revenue Service (IRS) website, where a comprehensive collection of tax forms and instructions is available. This ensures that you have access to the most current version with accompanying guidelines critical for accurate completion. For individuals preferring offline options, local IRS offices provide physical copies upon request. Furthermore, tax software such as TurboTax or QuickBooks often includes this form as part of their tax filing packages, streamlining the process by integrating it into their digital workflow.
Filling out Form Losses 2017 involves a series of detailed steps. Begin by gathering all the necessary transaction records, ensuring you have accurate purchase and sale dates, as well as corresponding amounts. Calculate your capital losses by subtracting the sale price from the purchase price for each asset sold. Distinguish between short-term and long-term transactions and enter these figures into the appropriate sections. Verify all calculations meticulously to prevent errors. If using tax preparation software, the built-in functionality will prompt you for the required information and automatically perform the necessary calculations.
Form Losses 2017 is predominantly used by taxpayers, including individuals and various business entities, who have participated in the sale of capital assets within the tax year and have incurred a loss. This group often includes investors, stock traders, and real estate professionals. Businesses structured as corporations, LLCs, partnerships, and sole proprietorships may also require this form to accurately reflect their capital transactions and ensure tax compliance. Understanding who primarily engages with this form highlights its essential role in both personal and business financial management.
Several critical terms are associated with Form Losses 2017, essential for understanding its completion and implications. These include:
Familiarity with these terms ensures accurate reporting and compliance with tax obligations.
The IRS provides clear guidelines for completing Form Losses 2017, ensuring that taxpayers can properly report their capital losses. These guidelines outline the necessary documentation, such as transaction receipts and financial statements, to support any claims made. Additionally, they specify the correct process for calculating net capital losses, including the detailed handling of carryover losses to future tax years. Adherence to these guidelines is crucial to prevent errors that could result in audits or penalties.
Timeliness is a critical factor when dealing with Form Losses 2017. The form must be submitted in conjunction with an individual or business’s annual tax return, typically due by April 15 each year. However, if this date falls on a weekend or legal holiday, the deadline is extended to the next business day. For those needing additional time, filing for an extension must be done prior to the original deadline, granting an additional six months to finalize returns and avoid late filing penalties.
To accurately complete Form Losses 2017, specific documents are imperative. These include:
Ensuring these documents are organized and readily available simplifies the completion process and supports claims during audits.
We've got more versions of the form losses 2017 form. Select the right form losses 2017 version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.6 Satisfied (46 Votes) | |
| 2024 | 4.4 Satisfied (56 Votes) | |
| 2023 | 4.7 Satisfied (48 Votes) | |
| 2022 | 4.2 Satisfied (24 Votes) | |
| 2021 | 4.8 Satisfied (151 Votes) | |
| 2020 | 4.4 Satisfied (230 Votes) | |
| 2019 | 4.2 Satisfied (143 Votes) | |
| 2018 | 4.3 Satisfied (108 Votes) | |
| 2017 | 4.4 Satisfied (145 Votes) | |
| 2016 | 4.3 Satisfied (99 Votes) | |
| 2015 | 4.4 Satisfied (33 Votes) | |
| 2014 | 4.1 Satisfied (60 Votes) | |
| 2013 | 4.2 Satisfied (67 Votes) | |
| 2012 | 4 Satisfied (40 Votes) | |
| 2011 | 4 Satisfied (60 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
2017 Passive Activity Loss. Caution: See the For Paperwork Reduction Act Notice, see separate instructions. Cat. No. 10356T. Form 8810 (2017)Read more
A deductible loss can occur from a vehicle or equipment accident, earthquake, a fire that was not willfully set by the taxpayer, flood, freeze, lightning,Read more
If this line is zero or more, stop here and include this form with your return; all losses are allowed, including any prior year unallowed losses entered onRead more


