



01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

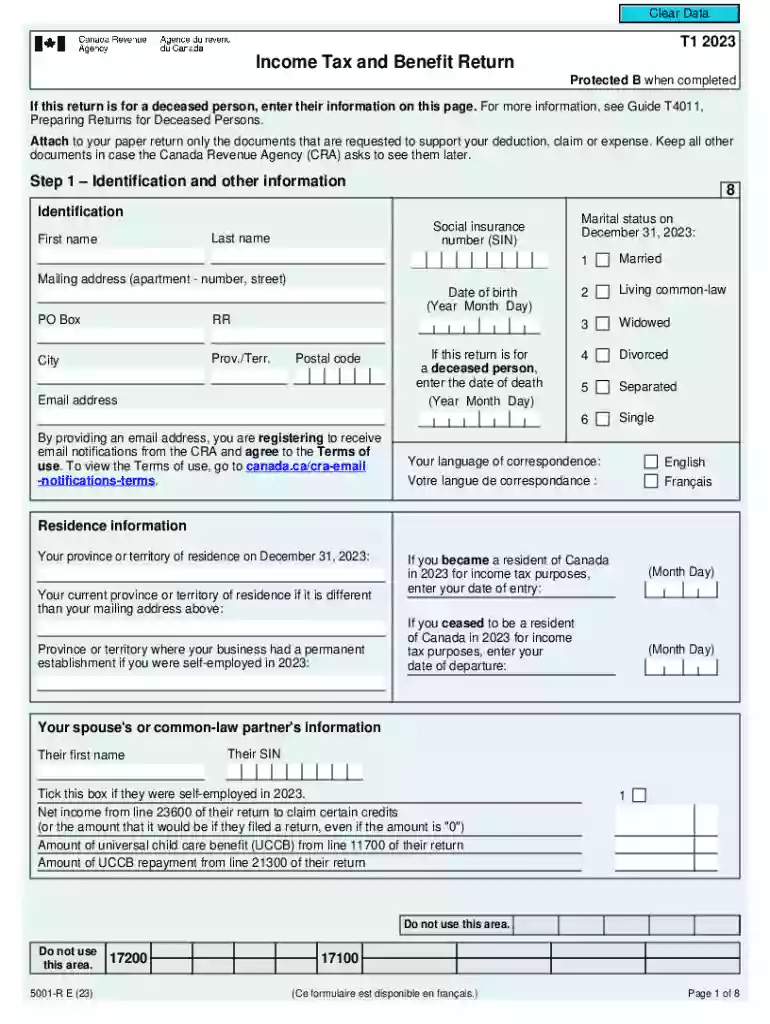
Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
The "Death of Taxpayer Prior to Filing Return" addresses a specific tax situation where an individual taxpayer passes away before their tax return for the fiscal year is filed. This form ensures that the taxpayer's tax obligations are fulfilled by either an executor, a surviving family member, or another authorized representative. The intention is to account for the taxpayer's income, deductions, and other relevant tax details, ensuring compliance with IRS regulations even after their passing.
To appropriately utilize this form, identify if the deceased taxpayer had any income or tax obligations for the year of their passing. An executor or authorized representative should compile all necessary financial documents, calculate any owed taxes, and prepare the tax return as they would if the taxpayer were still alive. Ensure you note the taxpayer's date of death on the return and include any available tax credits or deductions to accurately reflect the final tax liability or refund.
When filing a tax return on behalf of a deceased taxpayer, several documents are essential to ensure all relevant information is reported and obligations fulfilled:
Completing the "Death of Taxpayer Prior to Filing Return" involves a series of critical actions to ensure compliance with IRS regulations:
The IRS provides specific guidelines regarding the "Death of Taxpayer Prior to Filing Return":
Understanding important terms can facilitate dealing with a deceased taxpayer's return:
Timely submission of the deceased taxpayer's return is essential. Generally, the return must be filed by April 15th of the year following the taxpayer's death. If more time is needed, apply for an extension using Form 4868, which extends the deadline by six months. Be aware of any state-specific deadlines that may apply.
Failing to file the "Death of Taxpayer Prior to Filing Return" correctly or on time can result in various penalties:
Ensuring thorough compliance not only avoids these penalties but also respects the legal responsibilities associated with managing the deceased's financial obligations.
We've got more versions of the Death of Taxpayer Prior to Filing Return form. Select the right Death of Taxpayer Prior to Filing Return version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
You must report income, gain, or loss from all taxable transactions involving virtual currency on your federal income tax return for the taxable year of the
Returns made under section 6018(a) (relating to estate taxes) shall be filed within 9 months after the date of the decedents death.
On the final tax return, the surviving spouse or representative should note that the person has died. The IRS doesnt need a copy of the death certificate orRead more


