

01. Edit your medisave contribution form for self employed person online
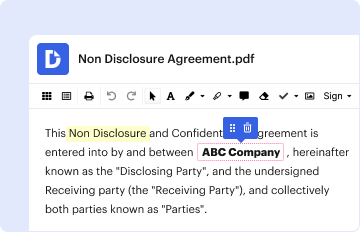
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send cpf self employed via email, link, or fax. You can also download it, export it or print it out.
The CPF for self-employed individuals primarily refers to the Central Provident Fund, a mandatory savings scheme in some countries, but has no affiliation with any U.S.-based regulatory body. For self-employed professionals, this concept typically pertains to managing personal retirement savings, healthcare provisions, and income protection. In jurisdictions using CPF, it functions as a mechanism for ensuring that self-employed individuals save adequately for retirement, adhere to mandated health insurance coverage, and manage fiscal obligations responsibly.
Securing a CPF account as a self-employed individual involves several steps, generally commencing with registration or enrollment into the national provident fund system of the individual's country. This process typically requires valid identification, proof of self-employment status, and documentation such as a business registration certificate or tax identification number. Each country has its own procedures and requirements, which can include online registration, submission of physical documents, or interfacing with local government agencies to initiate the process.
Determine Contribution Rate: Calculate your contribution rate based on your income level and your country's specific guidelines for self-employed individuals.
Register or Update Personal Information: Ensure your personal details, such as contact information and income status, are up to date within the CPF system to avoid any discrepancies.
Income Declaration: Report your annual or periodic income to ascertain the precise amount you need to contribute. This is critical for aligning with compliance and tax obligations.
Contribute Regularly: Follow the prescribed contribution schedule. Depending on local laws, this could be monthly, quarterly, or annually.
Keep Records: Maintain comprehensive documentation of your income declarations and contributions for financial audits and personal tracking.
CPF systems play a crucial role in ensuring financial stability for self-employed individuals. Unlike salaried employees, the self-employed manage their retirement funds, and CPF contributions often cover essential savings components like health insurance, emergency funds, and post-retirement income. Regular contributions provide a systematic approach to savings, helping mitigate the risks of inadequate funds during retirement or in situations requiring financial support.
Typical users of CPF systems include freelancers, independent contractors, small business owners, gig economy workers, and professionals who operate outside conventional employment frameworks. These individuals leverage CPF accounts to align their financial plans with retirement, health, and social security needs, despite lacking direct employer-based benefits. This system empowers them to build sustainable savings portfolios.
Understanding key terms related to CPF helps navigate its intricacies:
Self-employed individuals must comply with specified legal guidelines surrounding CPF systems, which can include mandatory contribution rates, self-reporting of income, and tax obligations related to these contributions. Legal stipulations ensure that self-employed persons are afforded similar benefits and protections as those available to salaried employees, strengthening their social security frameworks.
While CPF is not directly overseen by the U.S. IRS, U.S.-based self-employed professionals must align their tax filings with IRS stipulations, considering contributions to retirement and health savings accounts akin to CPF. Familiarity with IRS regulations and provisions related to self-employment tax, retirement savings plans, and health insurance deductions is essential to ensure compliance and optimize personal financial planning.
Most CPF systems enforce specific deadlines for income declaration and contributions. These dates typically align with annual tax filing deadlines and other national fiscal timelines. Awareness and adherence to these important dates ensure compliance with contributions and prevent penalties for late payments or misreporting.
Practical cases illustrate how self-employed individuals benefit from CPF systems:
In summary, understanding and managing CPF contributions are essential for self-employed individuals to secure their retirement funds and meet health and financial obligations commensurate with their income. Comprehensive planning and compliance with administrative guidelines provide significant long-term benefits, extending security and financial independence.
We've got more versions of the medisave contribution form for self employed person form. Select the right medisave contribution form for self employed person version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
The Chore-Time Circulating Pan Feeder (CPF) Feeding System is designed to feed poultry types. Using this equipment for any other purpose or in a way not within
Mar 6, 2023 Employees, jobseekers and the self-employed can all benefit from it. The CPF is available as long as the applicant does not claim his or her
40% of the supplement is paid as a cash benefit (10% if self-employed) and 60% is paid to the CPF account (90% to the MediSave account if self-employed).


