




01. Edit your form online
Type text, add images, blackout confidential details, add comments, highlights and more.

Type text, add images, blackout confidential details, add comments, highlights and more.

Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

Send it via email, link, or fax. You can also download it, export it or print it out.
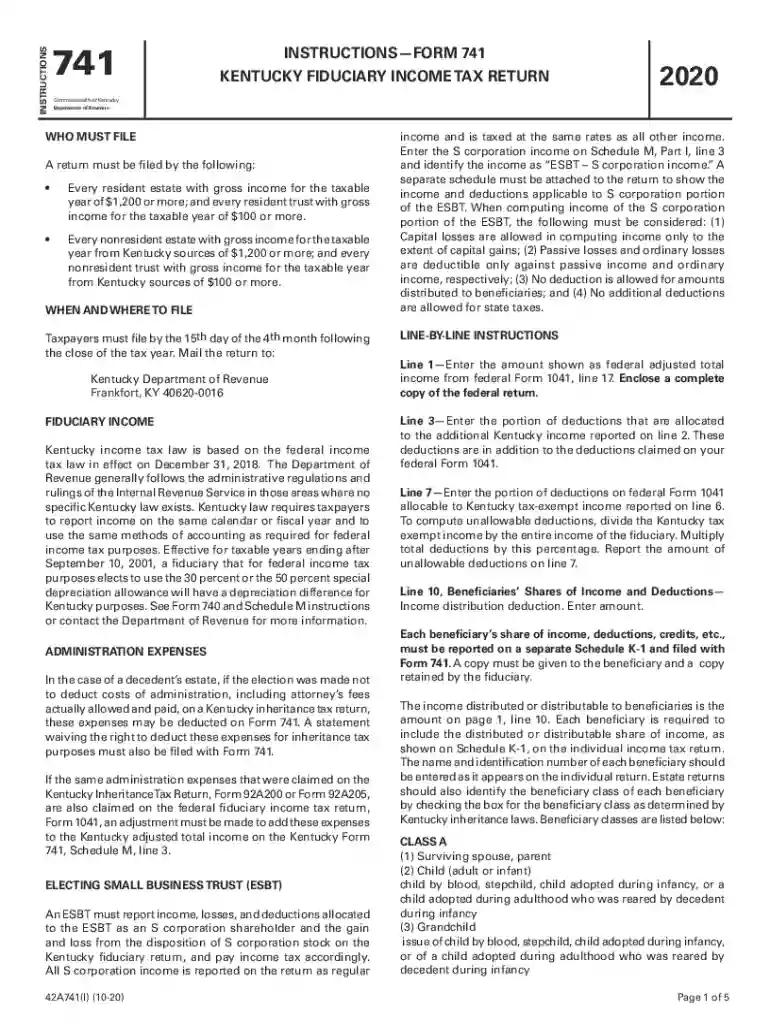
The term "from Kentucky sources of $100 or more" primarily refers to financial or taxable income originating from sources within the state of Kentucky that meet or exceed the threshold of $100. This definition can encompass various forms of income, such as wages, interest, dividends, rents, royalties, and business income. Residents and nonresidents earning income from Kentucky may need to report these earnings for state tax purposes, depending on the applicable regulations and thresholds established by the Kentucky Department of Revenue.
Utilizing the "from Kentucky sources of $100 or more" form involves accurately reporting income derived from the specified sources within Kentucky. Taxpayers should ensure they collect all relevant financial documents that detail earnings from Kentucky-based activities or investments.
Filing the form requires methodical steps to ensure compliance with tax obligations. Below is a general process for completing this requirement:
Familiarity with terms associated with this form is crucial for effectively managing state taxation obligations:
Kentucky imposes several guidelines that differ from federal tax rules to address state-specific taxation requirements:
Failure to abide by Kentucky tax regulations may result in fines or interest charges. It is imperative for individuals and fiduciaries alike to understand the consequences of late filing or non-reporting of income from Kentucky sources.
Consider scenarios where different individuals or entities interact with this form:
A Kentucky resident earning wages from an employer in the state must report the income as Kentucky source income.
A nonresident investor who receives dividends from a Kentucky-based corporation needs to declare this income if it meets the $100 requirement.
Proper documentation is critical in accurately reporting income from Kentucky sources and ensuring compliance:
Failure to report or inaccurately reporting income can result in various penalties:
By addressing each of these points, users of the form can comprehensively understand their responsibilities and the steps required to remain compliant with Kentucky tax laws.
We've got more versions of the from Kentucky sources of $100 or more form. Select the right from Kentucky sources of $100 or more version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2024 | 4.2 Satisfied (54 Votes) | |
| 2023 | 4.5 Satisfied (52 Votes) | |
| 2022 | 4.6 Satisfied (56 Votes) | |
| 2021 | 4.8 Satisfied (99 Votes) | |
| 2020 | 4.4 Satisfied (20 Votes) | |
| 2019 | 4.1 Satisfied (29 Votes) | |
| 2017 | 4.2 Satisfied (63 Votes) | |
| 2016 | 4 Satisfied (67 Votes) | |
| 2015 | 3.9 Satisfied (33 Votes) | |
| 2015 | 3.9 Satisfied (33 Votes) | |
| 2014 | 4.4 Satisfied (46 Votes) | |
| 2013 | 4.4 Satisfied (32 Votes) | |
| 2012 | 4 Satisfied (34 Votes) | |
| 2011 | 4 Satisfied (53 Votes) | |
| 2010 | 4.1 Satisfied (51 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
As of February 2011, coal is the source of 92 percent of the states electricity, and brings in $3.5 billion in export revenue.[1]
Section 6. Nonresident Estate or Trust. A nonresident estate with gross income for the taxable year from Kentucky sources of $1,200 or more and a nonresident
Every resident estate with gross income for the taxable year of $1,200 or more; and every resident trust with gross income for the taxable year of $100 or more.


