

01. Edit your form online
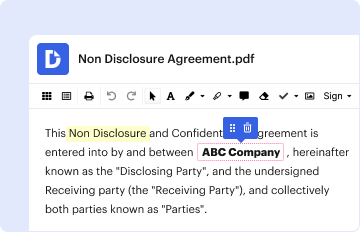
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
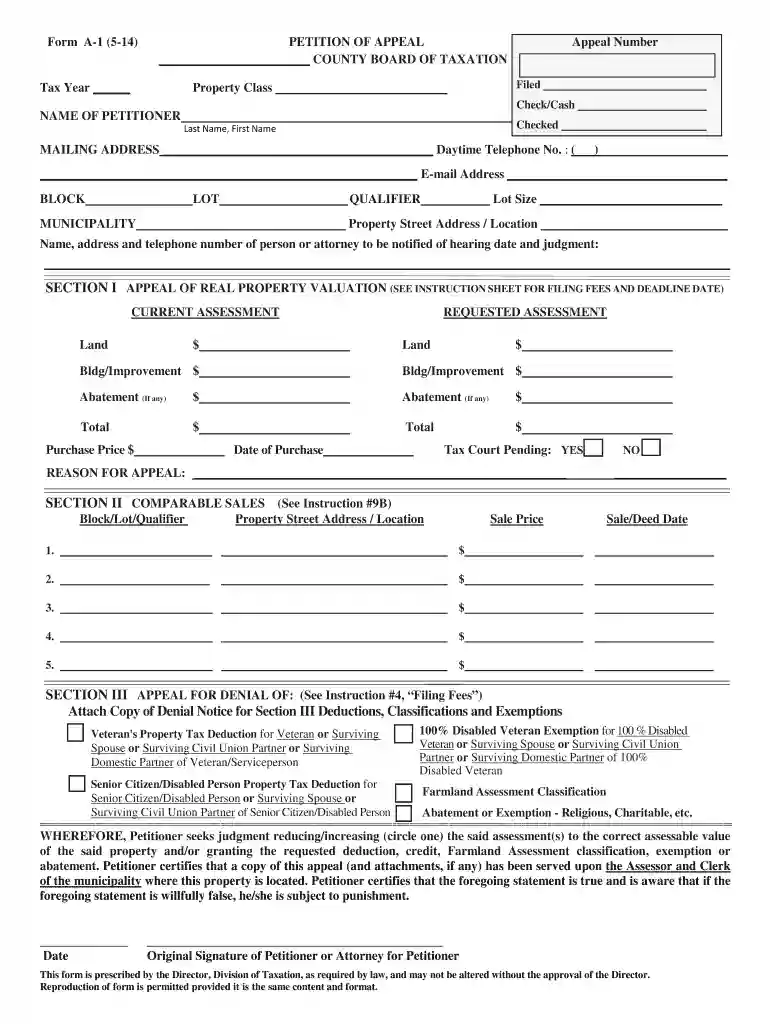
The NJ Form A-1 2014 is a Petition of Appeal document primarily used in New Jersey to contest real property valuations and tax assessments. This form provides a structured means for taxpayers to challenge the assessed value of their property by offering necessary details such as personal information, property specifics, and a comparison of current versus requested assessments. It also allows for the inclusion of comparable sales data to support the petition. The goal is to ensure fairness in property tax obligations by allowing property owners to present their case to the relevant tax appeal board.
To effectively utilize the NJ Form A-1 2014, follow these essential steps:
Gather Required Information: Collect personal details, property information, and current tax assessments. Prepare any evidence or comparable sales data that supports your case for reassessment.
Complete the Form: Fill out all sections of the form with accurate and detailed information. Double-check all entered data for accuracy.
Supporting Documentation: Attach additional documents that strengthen your appeal, such as appraisals or recent sales comparisons.
Submit the Form: Deliver the completed form and supporting documents to the appropriate county tax board. Ensure submission occurs before filing deadlines to maintain eligibility for review.
By adhering to these steps, you can improve the likelihood of a successful property tax appeal.
Completing the NJ Form A-1 2014 involves a series of detailed actions:
Identify Personal Information: Provide your name, address, and contact information to establish the petitioner's identity.
Property Details: Clearly document the property's location, description, and current assessed value.
Assessment Information: Record the existing tax assessment and clearly state the revised amount you are requesting.
Explanation of Appeal: Include a thorough explanation of why you believe the assessment is incorrect, referencing comparable property data or supporting appraisals.
Filing and Fees: Identify the correct filing fee and attach it to ensure the processing of your appeal.
Submission: Submit the form by mail or in person to the county board of taxation before the designated deadline.
Each step is critical for ensuring a comprehensive and valid appeal submission.
Understanding and adhering to filing deadlines is vital for the NJ Form A-1 2014:
Missing any of these deadlines could result in the automatic denial of your appeal, thereby reinforcing the importance of timely submission.
Submitting the NJ Form A-1 2014 necessitates several critical documents:
This documentation serves to validate your claims, making them more compelling to the reviewing body.
Understanding the options for submitting the NJ Form A-1 2014:
Choose the method that best aligns with your schedule and resources, ensuring timely receipt by the county board of taxation.
Failure to comply with the NJ Form A-1 2014 requirements can result in several penalties:
Understanding and adhering to all form requirements is crucial to securing a fair hearing and potential reassessment.
The NJ Form A-1 2014 must be used within specific legal boundaries:
Correct and legal usage dictates that the form is filled out truthfully, supported by evidence, and compliant with state guidelines.
We've got more versions of the nj form a 1 2014 form. Select the right nj form a 1 2014 version from the list and start editing it straight away!
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Sep 1, 2020 Form A(1). Uniform Interrogatories to be Answered by Plaintiff 2014 to be effective September 1, 2014; new interrogatory numbers 21 and.
Jun 18, 2025 The following contains forms in docHub PDF format for Employer Returns in New Jersey.
NJ Employee A worked in State B. (not subject to credit reduction) in January and then transferred to State. C (subject to credit reduction) on February 1.


