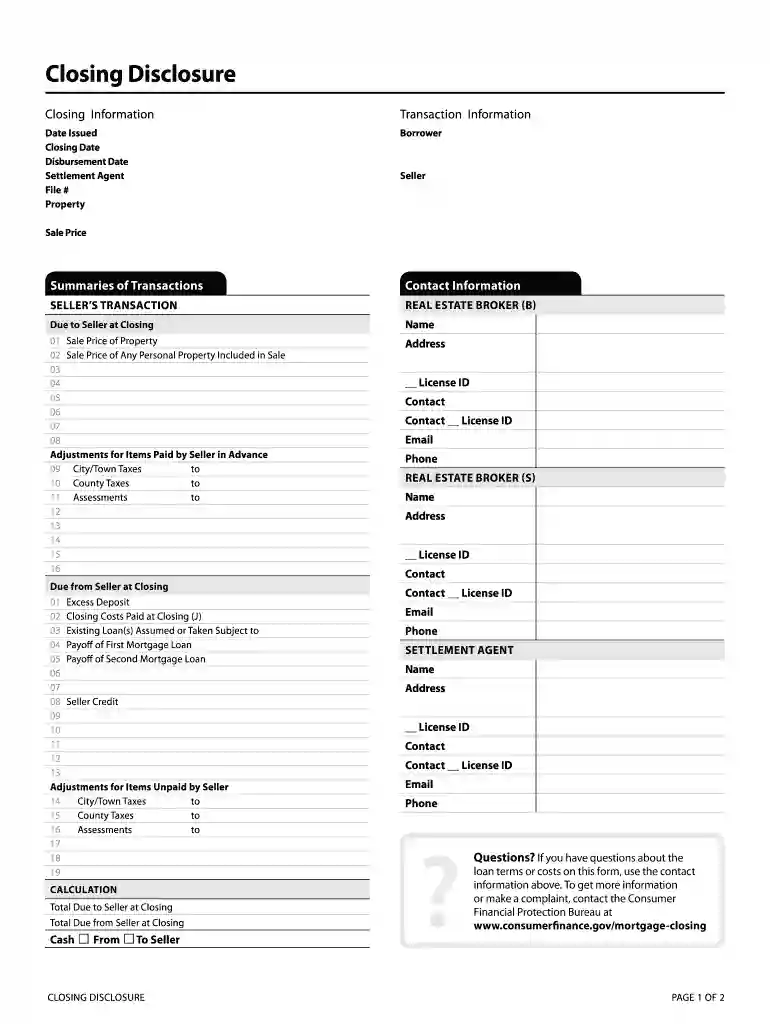
consumer cfpb closing disclosure Preview on Page 1

Consumer cfpb closing disclosure 2026

Here's how it works

  • 01. Edit your consumer cfpb closing disclosure online

    Type text, add images, blackout confidential details, add comments, highlights and more.

  • 02. Sign it in a few clicks

    Draw your signature, type it, upload its image, or use your mobile device as a signature pad.

  • 03. Share your form with others

    Send consumer cfpb closing form via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out consumer cfpb closing disclosure with our platform

Form edit decoration
9.5
Ease of Setup
DocHub User Ratings on G2
9.0
Ease of Use
DocHub User Ratings on G2
  1. Click ‘Get Form’ to open the consumer cfpb closing disclosure in the editor.
  2. Begin by filling in the 'Closing Information' section. Enter the 'Date Issued', 'Closing Date', and 'Disbursement Date'. Ensure that you accurately input details for the 'Settlement Agent' and 'File #'.
  3. Next, move to the 'Transaction Information' section. Fill in the property details and sale price. This information is crucial for clarity on financial obligations.
  4. In the 'Summaries of Transactions', complete both the seller's and buyer's transaction details. Include amounts due at closing, adjustments for taxes, and any credits applicable.
  5. Proceed to fill out the 'Closing Cost Details'. Break down loan costs into categories such as origination charges, services not shopped for, and other costs like taxes and prepaids.
  6. Review all entries for accuracy before finalizing. Utilize our platform’s features to save your progress or share it with relevant parties for review.

Start using our platform today to effortlessly complete your consumer cfpb closing disclosure online, for free!

be ready to get more

Complete this form in 5 minutes or less

Got questions?

We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.

The three-day rule for the delivery of the Closing Disclosure form is a part of the ``Know Before You Owe mortgage initiative from the Consumer Financial Protection Bureau (CFPB). This rule ensures that consumers receive this form with ample time to review it before the closing.
Monday. Tuesday. Wednesday. Preceding. Thursday. Preceding. Preceding. Monday. Preceding. Note: If a Federal Holiday falls in the three day period add a day for Disclosure The three day period is measured by days, not hours. Thus, Disclosures must be delivered three days be- fore closing and not 72 hours prior to closing.
Pre-consummation or account opening waiting period. A creditor must furnish 1026.32 disclosures at least three business days prior to consummation for a closed-end, high-cost mortgage and at least three business days prior to account opening for an open-end, high-cost mortgage.
A Closing Disclosure is a five-page form that provides final details about the mortgage loan you have selected. It includes the loan terms, your projected monthly payments, and how much you will pay in fees and other costs to get your mortgage (closing costs).
By law, you must receive a copy of your Closing Disclosure three business days prior to closing. Contact your lender or closing agent (title company, escrow officer, or attorney) at least a week before closing to find out how you will receive your Closing Disclosure.

Security and compliance

At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.

consumer cfpb closing form

Closing disclosure explainer

Oct 10, 2023 Lenders are required to provide your Closing Disclosure three business days before your scheduled closing. Use these days wiselynow is the timeRead more

Learn more
12 CFR 1026.38 - Content of disclosures for certain

This form is a statement of final loan terms and closing costs. Compare this document with your Loan Estimate.Read more

Learn more
If you believe that this page should be taken down, please follow our DMCA take down process here