

01. Edit your form online
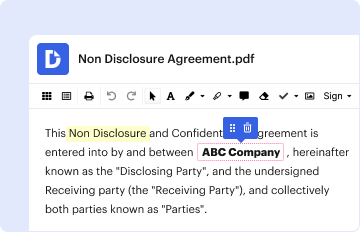
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
The nonresident credit, particularly applicable to individuals who live outside a certain state but earn income within it, plays a crucial role in tax filings. This credit is designed to prevent double taxation, where an individual might be taxed by both their state of residence and the state where the income was earned. For instance, if a person lives in New Hampshire but works in Maine, the nonresident credit on the Schedule NRH form allows for the proper apportionment of taxes, reflecting income earned in each state.
Collect Necessary Tax Forms: Gather Form 1040ME along with any relevant federal tax forms. These documents outline the income details needed for accurate calculations.
Calculate Total Income: Determine the total income earned outside your state of residence. This involves summing up wages, salaries, and other applicable incomes reported on your federal tax return.
Apportion Income: Use the Schedule NRH to apportion the income between the resident and nonresident states. Focus on detailing income earned specifically in the nonresident state.
Apply Adjustments and Deductions: Analyze any state-specific deductions or exemptions that may affect your tax liability. Adjust the earnings based on these factors to refine the taxable income amount.
Compute the Nonresident Credit: Use the apportioned and adjusted income figures to calculate the nonresident credit. Ensure all computations align with the guidelines specified for the form.
To access the Schedule NRH form, taxpayers can visit the official Maine Revenue Services website or their local tax office. It is often available in downloadable PDF format, which can be printed for manual completion or filled out using digital document editing tools like DocHub.
Each state may have unique regulations governing the calculation of the nonresident credit. In Maine, for instance, taxpayers need to abide by specific guidelines listed in the Schedule NRH instructions, which describe the income apportionment process. Therefore, it’s critical to review the state tax regulations to ensure compliance with local requirements.
The nonresident credit is a legally recognized means for taxpayers to avoid paying excessive state taxes on the same income. This credit is sanctioned by the Internal Revenue Code and is a practical tool used by taxpayers to manage their tax obligations fairly when residing and working in different states.
Taxpayers should align their filing of the Schedule NRH with the federal tax deadlines. For most individuals, the deadline is April 15 unless an extension is filed. Sticking to these timelines helps avoid late fees and ensures accurate tax reporting.
The Schedule NRH and accompanying documents can be submitted:
Self-Employed Individuals: If running a business from a nonresident state, they must calculate their income generosity to determine the amount taxable by each state.
Retirees: Retirees living in one state but receiving pension from another must account for this in their tax filings.
Students: Students working part-time in a different state than their domicile should correctly apply the nonresident credit to their work earnings.
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
The nonresident credit is computed by dividing the taxpayers Iowa source net income by the taxpayers total net income. See 701-Chapter 302 to determine aRead more
The nonresident credit is calculated on Schedule NR or Schedule NRH and entered on Form 1040ME, line 21. Note: Nonresident minimum taxability thresholds: ARead more
Note: All information must be in English. Show all amounts in U.S. dollars. File a separate Form 3520 for each foreign trust. For calendar year 2017,Read more


