

Here's how it works
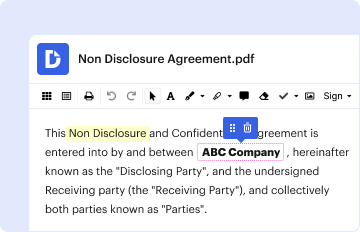
01. Edit your form 8865 instructions 2022 online
Type text, add images, blackout confidential details, add comments, highlights and more.
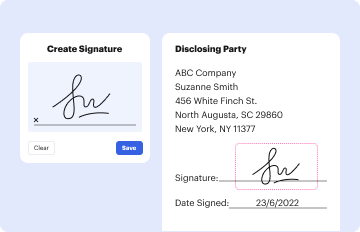
02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
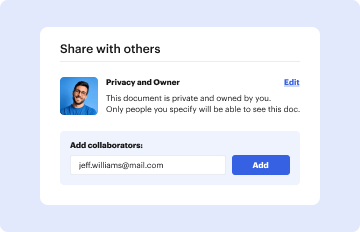
03. Share your form with others
Send 8865 instruction via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out 8865 instructions with our platform
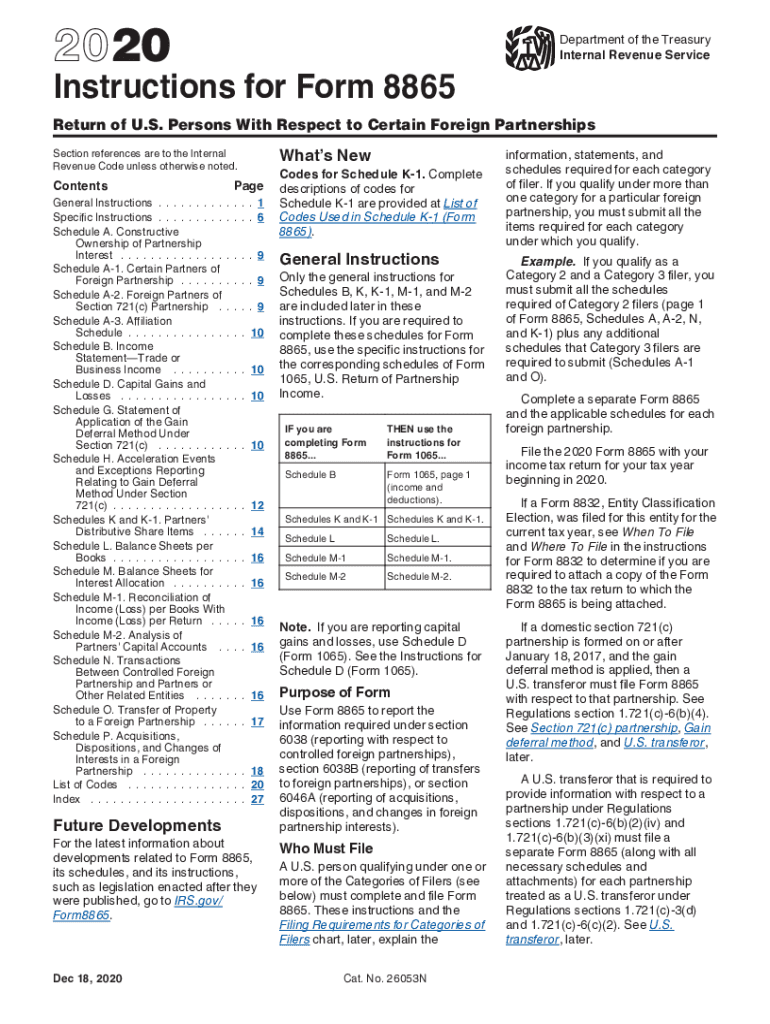
- Click ‘Get Form’ to open the 8865 instructions in the editor.
- Begin by reviewing the General Instructions section, which outlines who must file and the purpose of Form 8865.
- Identify your category of filer (Category 1, 2, 3, or 4) and check the corresponding box on page 1.
- Complete Schedule A to report constructive ownership of partnership interests. Ensure you list all relevant partners.
- Fill out Schedule B for income statements if applicable. If you have attached a copy of Form 1065, this step can be skipped.
- Proceed to complete Schedules K and K-1 for reporting distributive share items. Make sure to include all necessary details about each partner's share.
- Review all entries for accuracy before saving your document. Utilize our platform’s features to easily modify any sections as needed.
Start using our platform today for free to streamline your Form 8865 completion!
Fill out 8865 instructions online
It's free
It's free
See more 8865 instructions versions
We've got more versions of the 8865 instructions form. Select the right 8865 instructions version from the list and start editing it straight away!
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
What is controlled partnership?
Controlled Partnership means a limited partnership in which and so long as the Named Insured owns or controls, directly or indirectly, more than 50% of the limited partnership interest and in which a Company is the sole general partner.
What is the penalty for failing to file 8865?
Failure to timely file a Form 5471 or Form 8865 is generally subject to a $10,000 penalty per information return, plus an additional $10,000 for each month the failure continues, beginning 90 days after the IRS notifies the taxpayer of the failure, up to a maximum of $60,000 per return.
Where to enter 8865 in UltraTax?
From within UltraTax CS, create the electronic file for the Form 8865 return as you would for any other electronic return. With the filers client return open, choose Edit Electronic Filing Attachments. Click the Add button. In the Product field, select Federal from the drop-down list.
What is the filing requirement for a foreign partnership?
General Rule. A foreign partnership, for US tax purposes, must file Form 1065, US Return of Partnership Income, if either: The foreign partnership has gross income effectively connected with the conduct of a trade or business within the United States (effectively connected income); or.
What is the code 8865?
Code 8865 applies to employers engaged in operating group homes, drug or alcohol rehabilitation centers, halfway houses, homes for mentally disabled persons, temporary shelters and independent supportive living homes where no medical services are provided.
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


Related forms

DIVISION OF CORPORATIONS FEE SCHEDULE
The document outlines the fee schedule for various corporate services provided by the Delaware Department of State's Div ...
PDF FR 2910a Report Form - Federal Reserve Bank of Dallas
The document is the FR 2910a form, an Annual Report of Deposits and Reservable Liabilities required by the Federal Reser ...
Charitable Solicitation - Virginia Department of
The document is a complaint form provided by the Virginia Department of Agriculture and Consumer Services' Office of Cha ...
Leave Donation Form - wvde state wv
The document outlines the application process for employees in West Virginia to voluntarily donate their annual leave to ...
Oakland alarm permit
The document is an Alarm Registration Form for the Oakland Police Department's False Alarm Reduction Program. It include ...

Authorization card authorization card - National Association of - nail-union
The document is an authorization card allowing the National Association of Independent Labor (NAIL) to represent the sig ...
Care for Older Adult (COA) Assessment
The document is a Care for Older Adult (COA) Assessment form that includes patient information, medication reconciliatio ...
ORGAnscHAFtlicHE VERtREtER (WAHlAnZEiGE, 14 ABs
The document is a notification form for changes in the representation of a registered association (Verein) in Upper Aust ...
People also ask
What are the requirements for a controlled foreign partnership?
A foreign partnership is classified as a controlled foreign partnership (CFP) if more than 50% of its interests, either in terms of value or voting power, are owned by U.S. individuals who each own 10% or more of the partnership at any point during its tax year.
What are the requirements for a foreign corporation to be a controlled foreign corporation for US tax purposes?
Section 957 of the Internal Revenue Code defines a foreign corporation as being controlled if more than 50 percent of the total combined voting power of all classes of stock of such corporation entitled to vote, or more than 50 percent of the value of all its outstanding stock, is owned (directly, indirectly, or
What is the IRS definition of a foreign partner?
A foreign partnership is any partnership (including an entity classified as a partnership) that is not organized under the laws of any state of the United States or the District of Columbia or any partnership that is treated as foreign under the income tax regulations.