


01. Edit your 1042 2017 online
Type text, add images, blackout confidential details, add comments, highlights and more.
Type text, add images, blackout confidential details, add comments, highlights and more.
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
Send it via email, link, or fax. You can also download it, export it or print it out.
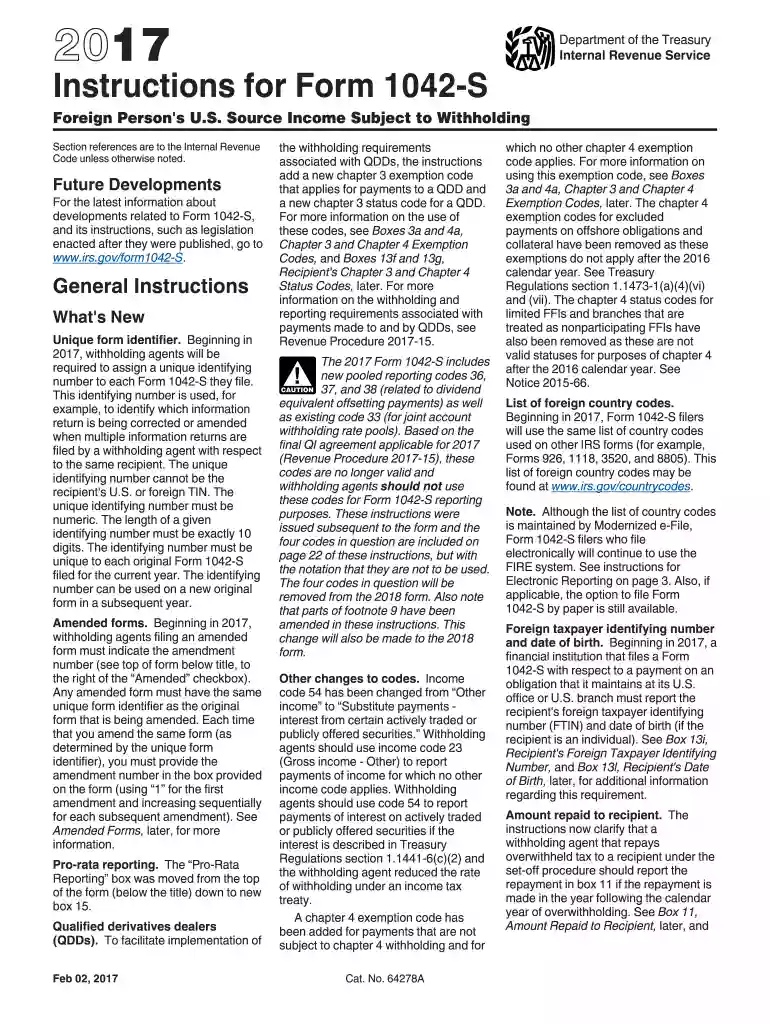
Form 1042-S, "Foreign Person’s U.S. Source Income Subject to Withholding," is a critical document used to report income paid to foreign individuals or entities that is subject to U.S. income tax withholding. This form serves multiple purposes: primarily, it captures various types of U.S.-sourced income, including interest, dividends, royalties, and compensation for services, which are paid to foreign persons. Additionally, it reflects the amount of U.S. tax withheld on those payments. Such reporting ensures compliance with U.S. tax regulations by both withholding agents and foreign recipients.
The form also provides a detailed breakdown of income types and withholding taxes applied, offering transparency and traceability of financial transactions involving foreign payees. Information on the form is utilized by the Internal Revenue Service (IRS) to verify that accurate taxes have been collected from foreign individuals earning U.S.-sourced income. By faithfully completing Form 1042-S, withholding agents can avoid penalties and aid foreign recipients in preparing their own tax returns.
To access Form 1042-S, withholding agents can visit the official IRS website, where they can download the form and its instructions in PDF format. The IRS's website remains the most reliable source for acquiring the form, ensuring that the latest version is used in compliance with current regulations.
Additionally, businesses may use authorized tax software that facilitates the generation of Form 1042-S as part of their taxation workflow. Reliable software solutions often offer guidance and workflows optimized to streamline the process of inputting data and managing multiple forms simultaneously. For entities relying on third-party payroll or tax preparation services, coordination with these providers can ensure timely and accurate form distribution.
Filling out Form 1042-S requires careful attention to specific parts of the form, each designed to gather detailed information about payments and withholding. Here is a step-by-step approach:
Identification of the Withholding Agent: Include the name and address of the entity responsible for the withholding. Also required is the agent's employer identification number (EIN).
Recipient Information: Enter the foreign recipient's name, address, and taxpayer identification number, which could be an individual taxpayer identification number (ITIN).
Income Type and Amount: Specify the type of income paid to the foreign individual or entity, using the income code corresponding to U.S. sourced income, and state the gross income amount.
Withholding Information: Detail the amount of U.S. federal tax withheld on the payment and provide the tax rate applied.
Exemption Codes and Legal Provisions: If the income is partially or fully untaxed under a tax treaty, include the applicable exemption codes and reference the precise legal provision.
By accurately completing each section, agents can ensure compliance and reduce the likelihood of misunderstandings or the need for amendments.
Several critical components of Form 1042-S distinguish it from other IRS forms. Key elements include:
These elements ensure that both the IRS and recipients can parse detailed tax information efficiently.
Form 1042-S is typically employed in various financial contexts. Common circumstances include:
Each of these scenarios requires correct documentation using Form 1042-S to ensure legal and tax compliance.
The deadline for providing Form 1042-S to recipients is March 15 of the year following the calendar year in which income was paid. Withholding agents must also file copies with the IRS by this date. If filing electronically, the IRS mandates the use of its Filing Information Returns Electronically (FIRE) system, which provides a streamlined method for submitting bulk forms. However, entities that file 250 or more forms are required to submit them electronically under IRS rules.
Timely filing is crucial, and entities that anticipate difficulties meeting the deadline should consider applying for an extension ahead of time.
Non-compliance with Form 1042-S filing obligations can result in significant penalties, including:
To mitigate risks, agents should ensure meticulous attention to detail when preparing forms and maintain a compliance checklist to routinely cross-verify all entries.
Withholding agents can submit Form 1042-S either digitally or by mail. Digital submission, especially for those filing 250 or more forms, is mandated by the IRS and facilitated through the FIRE system. Digital submission offers a streamlined, efficient, and timely method of filing that reduces paperwork and accelerates processing.
For fewer filings, or where digital submission is infeasible, paper submissions remain an option. Agents opting for paper must ensure mailing envelopes are postmarked by the due date to avoid late penalties. Digital preparation tools, like DocHub, simplify the transition from digital to paper, allowing for editable and printable documents.
To navigate the complexities of Form 1042-S, the IRS provides comprehensive guidelines detailing every section of the form. It advises on using the correct codes, exemption criteria, and appropriate documentation practices.
Additional resources, such as IRS instructions and guidelines, webinars, tax workshops, and bulletins, offer further clarity. Engaging with a tax professional well-versed in international taxation may also prove advantageous, providing tailored solutions and preventing costly oversights.
A firm grasp of these guidelines guarantees adherence to regulatory standards, minimizing financial risks associated with non-compliance.
We've got more versions of the 1042 2017 form. Select the right 1042 2017 version from the list and start editing it straight away!
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| 2025 | 4.3 Satisfied (22 Votes) | |
| 2024 | 4.7 Satisfied (37 Votes) | |
| 2023 | 4.6 Satisfied (41 Votes) | |
| 2022 | 4.8 Satisfied (155 Votes) | |
| 2020 | 4.4 Satisfied (187 Votes) | |
| 2019 | 4.3 Satisfied (88 Votes) | |
| 2018 | 4.2 Satisfied (88 Votes) | |
| 2017 | 4.2 Satisfied (72 Votes) | |
| 2016 | 4.4 Satisfied (545 Votes) | |
| 2015 | 4.3 Satisfied (67 Votes) | |
| 2013 | 4 Satisfied (29 Votes) | |
| 2012 | 4 Satisfied (25 Votes) |
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Dec 17, 2018 Social security and Medicare taxes apply to the wages of household workers you pay $2,100 or more in cash wa- ges for 2019.Read more
Feb 6, 2018 Violation of this rule is regarded as sufficient cause for dismissal. Page 3. Undergraduate Bulletin. 20172019. Via Marcantonio Colonna, 21.Read more


