

Here's how it works
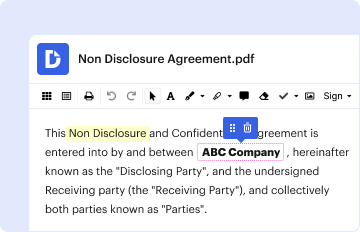
01. Edit your metlife non erisa 403 b withdrawal request online
Type text, add images, blackout confidential details, add comments, highlights and more.
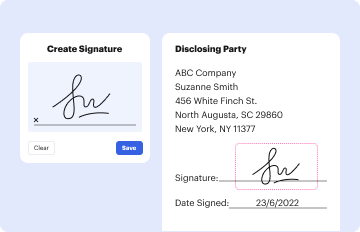
02. Sign it in a few clicks
Draw your signature, type it, upload its image, or use your mobile device as a signature pad.
03. Share your form with others
Send brighthouse non erisa 403 b withdrawal request via email, link, or fax. You can also download it, export it or print it out.
How to use or fill out NON-ERISA - 403(b) Withdrawal Request Form with our platform
- Click ‘Get Form’ to open it in the editor.
- Begin by filling out the 'General Information' section. Enter your name, Social Security Number, address, marital status, sex, daytime phone number, employer name, and contract number.
- In the 'Reason for Withdrawal' section, check all applicable boxes that explain why you are requesting a withdrawal. If you select age-related options, provide your date of birth and employment status.
- Specify the 'Amount and Source of Withdrawal.' Indicate whether you wish to withdraw your entire account balance or a partial amount. For partial withdrawals, specify the net or gross amount and how you want it allocated among investment options.
- Complete any necessary tax withholding instructions in sections 7 through 9 based on your situation. Ensure you understand the implications of withholding on your withdrawal.
- Review all entered information for accuracy before submitting. Once satisfied, click ‘Submit’ to finalize your request.
Start using our platform today to simplify your form completion process for free!
Fill out NON-ERISA - 403(b) Withdrawal Request Form online
It's free
It's free
See more NON-ERISA - 403(b) Withdrawal Request Form versions
We've got more versions of the NON-ERISA - 403(b) Withdrawal Request Form form. Select the right NON-ERISA - 403(b) Withdrawal Request Form version from the list and start editing it straight away!
Got questions?
We have answers to the most popular questions from our customers. If you can't find an answer to your question, please contact us.
Contact us
Can you make withdrawals from a 403b?
403(b) plans sponsored by 501(c)(3) organizations (such as tax-exempt hospitals and charitable organizations) are generally subject to ERISA but may choose non-ERISA if they meet specific requirements. In other words, they do not automatically qualify to be non-ERISA.
What is the difference between ERISA and non-ERISA?
Employers managing ERISA plans must act in your best interests, whereas non-ERISA plans often involve minimal employer involvement, putting more responsibility on the employee. Tax and contribution differences.
Is a 403b an ERISA?
Like 401(k) plans, 403(b) plans are account-based defined contribution plans sponsored by employers. Many 403(b) plans are subject to ERISA requirements and are intended to protect the interests of plan participants. However, some 403(b) plans are not covered by ERISA.
What is a non-ERISA 403b plan?
Such plans are commonly referred to as Non-ERISA plans. Non-ERISA 403(b) plans do not involve employer contributions, involve voluntary plan participation only, and do not need to follow the stipulations of the Act.
What is a non-ERISA 403 B?
Once you take a distribution from a 403(b), the plan must send you and the IRS a Form 1099-R. This form shows the total withdrawals you made from the account and the amount withheld (if any) for taxes.
Security and compliance
At DocHub, your data security is our priority. We follow HIPAA, SOC2, GDPR, and other standards, so you can work on your documents with confidence.
Learn more


People also ask
Whats the difference between a 401k and a 403b?
Contributions to traditional 401(k)s and 403(b)s are deducted from your paycheck pre-tax, and you only pay taxes when you withdraw money. The type of plan youre eligible for depends on your job. For-profit businesses generally offer 401(k) plans, while nonprofits generally offer 403(b) plans.